

1. Introduction
Optimal stopping problems have a long and storied academic history and have recently found various applications in modern practical domains that arise in technological platforms; see further discussion and references below. At the core, the problem can be stated as a sequential selection objective: given a horizon of length n, we observe sequentially random variables and need to stop them at some (random) time perceived to be associated with the largest value in the sequence. The objective is typically to identify such optimal stopping rules, but more practically to also consider rules that are perhaps suboptimal but simple in structure, broad in scope of application, and enjoy theoretical performance guarantees. Let us now formalize this set up.
1.1. Optimal stopping
Let $X_1, \ldots, X_n$
be integrable, independent, non-negative random variables defined on the probability space $(\Omega, {\mathscr F}, {\mathbb P})$
with joint distribution function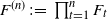 $F^{(n)}\,:\!=\,\prod_{t=1}^nF_t$
. Let ${\mathscr X}_t$
be the $\sigma$
-field generated by $X_1, \ldots, X_t$
,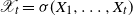 ${\mathscr X}_t=\sigma(X_1, \ldots, X_t)$
, $1\leq t\leq n$
, and let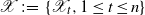 ${\mathscr X}\,\,:\!=\,\{{\mathscr X}_t, 1\leq t\leq n\}$
be the corresponding filtration. By definition, a stopping time $\tau$
with respect to ${\mathscr X}$
is a random variable on $(\Omega, {\mathscr F}, {\mathbb P})$
such that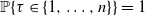 ${\mathbb P}\{\tau \in \{1, \ldots, n\}\}=1$
and $\{\tau=t\} \in {\mathscr X}_t$
for all $1\leq t\leq n$
. The set of all stopping times with respect to filtration ${\mathscr X}$
is denoted ${\mathscr T}_{\rm all}$
.
The reward of a given stopping time $\tau\in {\mathscr T}_{\rm all}$
is defined by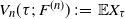 $V_n(\tau;\, F^{(n)})\,:\!=\, \mathbb E X_{\tau}$
. The problem of optimal stopping is to find a stopping rule $\tau^*$
such that
 \begin{equation*} V_n(\tau^*;\, F^{(n)}) = V_n^*({\mathscr T}_{\rm all};\, F^{(n)}) \,:\!=\, \sup\nolimits_{\tau \in {\mathscr T}_{\rm all}} \mathbb E X_{\tau}.\end{equation*}
It is well known [Reference Chow, Robbins and Siegmund4] that the optimal stopping rule $\tau^*$
is given by
 \begin{align*} \tau^* \,:\!=\, \min\{1\leq t \leq n-1\colon X_t \geq v_{n-t}\}, \end{align*}
and $\tau^*=n$
otherwise. Here the sequence of thresholds $\{v_t\}$
is defined by backward induction,
 \begin{align*}v_1=\mathbb E X_n, \qquad v_{t+1}=\mathbb E \{X_{n-t}\vee v_t\}, \quad t=1,\ldots,n-1, \end{align*}
and the optimal value of the problem is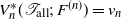 $V_n^*({\mathscr T}_{\rm all};\, F^{(n)})=v_n$
.
1.2. Prophet inequalities and minimax formulation
In any specific problem instance when $F^{(n)}$
is given, the optimal stopping rule $\tau^*$
and the optimal value $V_n^*({\mathscr T}_{\rm all};\, F^{(n)})$
can be computed numerically. However, in general, it is difficult to assess the performance of optimal stopping rules, and prophet inequalities are very useful tools for this purpose. Prophet inequalities compare the optimal value of the stopping problem with the expected value of the maximal observation,
 \begin{align*}M_n(F^{(n)}) \,:\!=\, \mathbb E \max\nolimits_{1\leq t\leq n} X_t.\end{align*}
This is the performance of the ‘prophet’ with complete foresight. There are two commonly used measures of stopping rule performance relative to the prophet: ratio-type and difference-type prophet inequalities.
Let $\mathcal{F}^{(n)}$
be a family of distribution functions on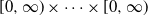 $[0,\infty)\times\cdots\times[0,\infty)$
, and let ${\mathscr T}$
be a class of stopping rules of ${\mathscr X}$
. The competitive ratio of a stopping rule $\tau\in {\mathscr T}$
under distribution $F^{(n)}\in \mathcal{F}^{(n)}$
is defined by
 \begin{align*} \mathcal{R}_n(\tau;\, F^{(n)}) = \frac{V_n(\tau;\, F^{(n)})}{M_n(F^{(n)})}. \end{align*}
The competitive ratio is well defined unless $X_1, \ldots, X_n$
are all identically zero; this trivial case is excluded from consideration. The optimal stopping rule $\tau^*$
in class ${\mathscr T}$
for given $F^{(n)}$
satisfies
 \begin{align*} \mathcal{R}_n(\tau^*;\, F^{(n)})=\mathcal{R}_n({\mathscr T\,};\, F^{(n)})\,:\!=\,\sup\nolimits_{\tau\in {\mathscr T}}\mathcal{R}_n(\tau;\, F^{(n)}). \end{align*}
A ratio-type prophet inequality associated with the class of stopping rules ${\mathscr T}$
and family of distributions $\mathcal{F}^{(n)}$
is a lower bound on $\mathcal{R}_n({\mathscr T\,};\, F^{(n)})$
uniform over $F^{(n)}\in \mathcal{F}^{(n)}$
:
 \begin{equation} \mathcal{R}_n({\mathscr T\,};\, F^{(n)}) \geq \psi_n \quad \mbox{for all}\ F^{(n)}\in \mathcal{F}^{(n)},\end{equation}
where $\{\psi_n\}$
is a numerical sequence with values in (0, 1]. The worst-case competitive ratio of the optimal rule in ${\mathscr T}$
over the family of distributions $\mathcal{F}^{(n)}$
is
 \begin{align*}\mathcal{R}_n^*({\mathscr T\,};\,\mathcal{F}^{(n)}) = \inf_{F^{(n)}\in \mathcal{F}^{(n)}} \mathcal{R}_n({\mathscr T\,};\,\,F^{(n)})=\inf_{F^{(n)}\in \mathcal{F}^{(n)}} \sup\nolimits_{\tau\in {\mathscr T}}\mathcal{R}_n(\tau;\, F^{(n)}). \end{align*}
We say that a ratio-type prophet inequality (1) is asymptotically sharp if
 \begin{equation} \lim_{n\to\infty} \big\{\psi_n^{-1} \mathcal{R}_n^*({\mathscr T\,};\,\, \mathcal{F}^{(n)})\big\} = 1.\end{equation}
Asymptotically sharp difference-type prophet inequalities are defined similarly. First, consider the regret of a stopping rule $\tau\in {\mathscr T}$
under $F^{(n)}\in \mathcal{F}^{(n)}$
to be the difference between the prophet performance and the reward of $\tau$
,
 \begin{align*}\mathcal{A}_n(\tau;\, F^{(n)})\,:\!=\,M_n(F^{(n)})- V_n(\tau;\, F^{(n)}),\end{align*}
and the regret of the optimal stopping rule for given $F^{(n)}$
is
 \begin{align*} \mathcal{A}_n({\mathscr T\,};\, F^{(n)})\,:\!=\,\inf_{\tau\in {\mathscr T}}\mathcal{A}_n(\tau;\,\mathcal{F}^{(n)})=\inf_{\tau\in {\mathscr T}}\, \{M_n(F^{(n)})- V_n(\tau;\, F^{(n)})\}. \end{align*}
The difference-type prophet inequality associated with the class of stopping rules ${\mathscr T}$
and family of probability distributions $\mathcal{F}^{(n)}$
is an upper bound on the regret of the optimal stopping rule which holds uniformly over $F^{(n)}\in \mathcal{F}^{(n)}$
:
 \begin{equation} \mathcal{A}_n({\mathscr T\,};\, F^{(n)}) \leq \delta_n \quad \mbox{for all}\ F^{(n)}\in \mathcal{F}^{(n)},\end{equation}
where $\{\delta_n\}$
is a non-negative numerical sequence. The worst-case regret over a family $\mathcal{F}^{(n)}$
of distributions is
 \begin{align*}\mathcal{A}_n^*({\mathscr T\,};\,\mathcal{F}^{(n)})\,:\!=\,\sup\nolimits_{F^{(n)}\in\mathcal{F}^{(n)}}\mathcal{A}_n({\mathscr T\,};\,\,F^{(n)}),\end{align*}
and the difference-type prophet inequality is said to be asymptotically sharp if
 \begin{equation} \lim_{n\to\infty}\big\{\delta_n^{-1} \mathcal{A}_n^*({\mathscr T\,};\,\, \mathcal{F}^{(n)})\big\} =1.\end{equation}
There is a great deal of interest in the derivation of asymptotically sharp prophet inequalities and the determination of sequences $\{\psi_n\}$
and $\{\delta_n\}$
for various families of distributions and classes of stopping rules. Recently there has been a renewed interest in the topic in view of applications of optimal stopping theory in economics and computer science. For a comprehensive review of the area and for additional pointers to the literature we refer to [Reference Harten, Meyerthole and Schmitz13] and to the surveys [Reference Correa, Foncea, Hoeksma, Oosterwijk and Vredeveld5, Reference Hill and Kertz17]. Below we discuss selected results that are most relevant to our study.
1.2.1. Prophet inequalities for optimal stopping rules
The classical ratio-type prophet inequality [Reference Krengel and Sucheston22] states that, for any joint probability distribution $F^{(n)}=\prod_{t=1}^n F_t$
,
 \begin{equation} \mathcal{R}_n\big({\mathscr T}_{\rm all};\, F^{(n)}\big) \geq \frac{1}{2}.\end{equation}
Let $\mathcal{F}^{(n)}_{[0,\infty)}$
be the family of all possible product-form distributions with marginals supported on $[0,\infty)$
. Then the prophet inequality (5) is asymptotically sharp over $\mathcal{F}_{[0,\infty)}^{(n)}$
:
 \begin{equation} \lim_{n\to\infty} \mathcal{R}^*_n \big({\mathscr T}_{\rm all};\, \mathcal{F}_{[0,\infty)}^{(n)}\big)= \frac{1}{2}.\end{equation}
In words, for any $F^{(n)}$
the optimal reward of stopping rules in the class ${\mathscr T}_{\rm all}$
is at least within a factor of $\frac12$
of the value that can be achieved by the prophet with complete foresight, and there exists a distribution $F_*^{(n)}$
such that this factor cannot be improved upon asymptotically as n tends to infinity. We refer to [Reference Krengel and Sucheston22]; see also the survey [Reference Hill and Kertz17] for detailed discussion.
As for the difference-type prophet inequalities, [Reference Hill and Kertz14] considered the family $\mathcal{F}^{(n)}_{[0,1]}$
of all product-form distributions with marginals supported on [0,1] and showed that
 \begin{equation} \mathcal{A}_n({\mathscr T}_{\rm all};\, F^{(n)}) \leq \frac{1}{4} \quad \text{for all}\ F^{(n)}\in \mathcal{F}_{[0,1]}^{(n)}.\end{equation}
This inequality is asymptotically sharp, i.e.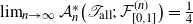 $\lim_{n\to\infty}\mathcal{A}^*_n\big({\mathscr T}_{\rm all};\, \mathcal{F}_{[0,1]}^{(n)}\big) =\frac{1}{4}$
. The choice of the class $\mathcal{F}_{[0,1]}^{(n)}$
was motivated by [Reference Hill and Kertz14], given that if the support is unbounded then the regret can be arbitrarily large. A case with unbounded support was in fact considered by [Reference Kennedy and Kertz20], which focused on the family $\mathcal{F}_\sigma^{(n)}$
of all distributions $F^{(n)}=\prod_{t=1}^n F_t$
with marginals having bounded variance,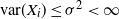 ${\rm var}(X_i)\leq \sigma^2<\infty$
, $i=1, \ldots, n$
. It was proved that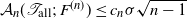 $\mathcal{A}_n({\mathscr T}_{\rm all};\, F^{(n)}) \leq c_n \sigma \sqrt{n-1}$
for all $F^{(n)}\in \mathcal{F}^{(n)}_\sigma$
, where $c_n\leq \frac12$
and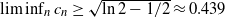 $\liminf_n c_n\geq \sqrt{\ln 2- 1/2}\approx 0.439$
. However, no statement on the sharpness of this inequality was made. To the best of our knowledge, the problem of deriving such results in more general (than bounded support) settings remains open.
If $X_1, \ldots, X_n$
is a sequence of independent identically distributed (i.i.d.) random variables with common distribution F, then the prophet inequalities (5) and (7) can be improved. It is worth noting, however, that proofs of sharpness in this case are more involved because the family of distributions is much narrower given the homogeneity assumption. In what follows, in the setting of i.i.d. random variables, with a slight abuse of notation in all formulas we drop the superscript (n) and replace $F^{(n)}$
by F, $\mathcal{F}^{(n)}$
by $\mathcal{F}$
, etc.
In this setting, [Reference Hill and Kertz16] shows that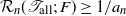 $\mathcal{R}_n({\mathscr T}_{\rm all};\, F) \geq {1}/{a_n}$
for all $F\in \mathcal{F}_{[0,\infty)}$
, with the numerical constants $\{a_n\}$
satisfying $1.1 <a_n<1.6$
. This result was strengthened in [Reference Kertz21] by providing a sharp characterization of the region where pairs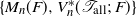 $\{M_n(F), V_n^*({\mathscr T}_{\rm all};\, F)\}$
may take values. In particular, it follows from the results in this paper that
 \begin{equation*} \lim_{n\to \infty} \inf_{F\in \mathcal{F}_{[0,\infty)}} \mathcal{R}_n({\mathscr T}_{\rm all};\, F) \geq \frac{1}{1+\alpha_*}\approx 0.746,\end{equation*}
where the infimum is taken over all possible distributions, and $\alpha_*$
is the unique solution to the equation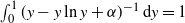 $\int_0^1 (y-y\ln y +\alpha)^{-1}\,\mathrm{d} y=1$
. We also refer to [Reference Correa, Foncea, Hoeksma, Oosterwijk and Vredeveld6] and [Reference Harten, Meyerthole and Schmitz13].
In the case of i.i.d. random variables, the difference-type prophet inequality (7) can be improved as well: [Reference Hill and Kertz16] showed that, for any F supported on [0,1] and for some universal constants $0 < b_n < \frac{1}{4}$
with $b_2\approx 0.0625$
, $b_{100}\approx 0.110$
, and $b_{10\,000}\approx 0.111$
,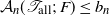 $\mathcal{A}_n({\mathscr T}_{\rm all};\, F) \leq b_n$
for all $F\in \mathcal{F}_{[0,1]}$
, and this inequality is asymptotically sharp. In particular, [Reference Hill and Kertz16, Proposition 5.3] presented extremal distributions for which the claimed sequence $\{b_n\}$
is attained.
1.2.2. Prophet inequalities for single-threshold stopping rules
One of the remarkable observations in this area is that an inequality such as (5) holds even if the class of all possible stopping rules ${\mathscr T}_{\rm all}$
is replaced by a much smaller class of simple stopping rules – the stopping rules with a single threshold. Specifically, let
 \begin{align*}{\mathscr T}_0\,:\!=\,\{\tau_0(\theta), \theta\geq 0\}, {\mathscr T}_1\,:\!=\,\{\tau_1(\theta), \theta\geq 0\}\end{align*}
be classes of single-threshold stopping rules such that
 \begin{equation} \tau_0(\theta) \,:\!=\, \min\{1\leq t\leq n-1\colon X_t> \theta\}, \qquad \tau_1(\theta) \,:\!=\, \min\{1\leq t\leq n-1\colon X_t\geq \theta\},\end{equation}
and $\tau_i(\theta)=n$
, $i=0,1$
, when the set is empty. The classes ${\mathscr T}_0$
and ${\mathscr T}_1$
are equivalent in terms of the performance of the corresponding stopping rules; taking this fact into account, in the following we use the notation ${\mathscr T}_{\rm s}$
for ${\mathscr T}_0$
or ${\mathscr T}_1$
. However, sometimes it will be convenient to distinguish between the classes ${\mathscr T}_0$
and ${\mathscr T}_1$
.
The main observation for the single-threshold stopping rules ${\mathscr T}_{\rm s}$
dates back to [Reference Samuel-Cahn26], which shows that the relations (5) and (6) remain true if ${\mathscr T}_{\rm all}$
is replaced by ${\mathscr T}_{\rm s}$
:
 \begin{equation} \mathcal{R}_n({\mathscr T}_{\rm s};\, F^{(n)}) \geq \tfrac{1}{2} \quad \text{for all}\ F^{(n)}\in \mathcal{F}^{(n)}_{[0,\infty)}\end{equation}
and $\lim_{n\to\infty}\mathcal{R}_n^*\big({\mathscr T}_{\rm s};\, \mathcal{F}_{[0,\infty)}^{(n)}\big) = \frac{1}{2}$
. It is evident that the lower bound (9) also holds in the i.i.d. case. In addition, [Reference Samuel-Cahn26, Theorem 2] proves that this bound is asymptotically sharp for the single-threshold rules even in the i.i.d. case: $\lim_{n\to\infty}\mathcal{R}^*_n\big({\mathscr T}_{\rm s};\, \mathcal{F}_{[0,\infty)}\big) = \frac{1}{2}$
. It turns out that the constant $\frac12$
can be improved for continuous distributions. In particular, let
 \begin{align*} \mathcal{C}_{[0,\infty)}\,:\!=\, \big\{F\colon F \hbox{ is continuous on } [0,\infty)\big\}; \end{align*}
then it follows from results in [Reference Correa, Foncea, Hoeksma, Oosterwijk and Vredeveld6] that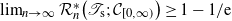 $\lim_{n\to \infty}\mathcal{R}_n^*\big({\mathscr T}_{\rm s};\,\mathcal{C}_{[0,\infty)}\big) \geq 1 - {1}/{{\mathrm{e}}}$
. We refer to [Reference Ehsani, Hajiaghayi, Kesselheim and Singla9] for analysis of the prophet inequality in the i.i.d. setting with constant $1-{\mathrm{e}}^{-1}$
, but for randomized single-threshold stopping rules.
We are not aware of any analogous results for difference-type prophet inequalities that establish optimality of single-threshold stopping rules. A more detailed discussion of sharpness of prophet inequalities in the i.i.d. setting for single-threshold stopping rules is given in Section 3.
1.3. Main contributions
The literature on prophet inequalities is vast and the topic has been extensively studied. Sharp prophet inequalities presented in the literature are typically asymptotically sharp in the sense of definitions (2) and (4), and they are derived for classes of all possible distributions $\mathcal{F}_{[0,\infty)}$
or $\mathcal{F}_{[0,1]}$
. The process usually follows two main steps: a stopping rule in a given class is proposed and a lower (upper) bound on the competitive ratio (regret) of the rule is derived for any distribution from the given class; then, a least favorable distribution is exhibited for which the derived bounds are (asymptotically) achieved. In general, very little is known about exact values of the worst-case competitive ratio and the worst-case regret in the non-asymptotic setting when the horizon n is fixed, or when one considers additional constraints on the class of underlying distributions.
In this work we focus on the i.i.d. setting and develop a unified and principled framework for the derivation of non-asymptotic sharp prophet inequalities for single-threshold stopping rules. We study randomized single-threshold stopping rules that aggregate the stopping rules $\tau_0(\theta)$
and $\tau_1(\theta)$
in (8) and allow much better performance to be achieved relative to the prophet. We show that for such rules the derivation of sharp prophet inequalities is equivalent to solving a two-person zero-sum infinite game on the unit square. Then, for any fixed problem horizon n the optimal value of the aforementioned game yields the sharp constant in the non-asymptotic prophet inequality, while the solution of the game provides both the least favorable distribution and the corresponding optimal single-threshold stopping rule. The developed framework supports simple computational procedures to derive sharp non-asymptotic prophet inequalities for restricted classes of distributions, characterizes numerical (discretization) errors in said computation, and illustrates their efficacy on an array of test problems.
1.4. Notation
Throughout the paper we use the following notation. Let F be a distribution function; then we define the quantile function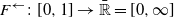 $F^{\leftarrow}\colon [0,1]\to \bar{{\mathbb R}}=[0, \infty]$
of F by
 \begin{align*} F^\leftarrow (t)\,:\!=\,\inf\{x\in [0,\infty)\colon F(x)\geq t\}, \quad 0 \leq t \leq 1. \end{align*}
The quantile function $F^\leftarrow$
is left continuous inverse to F. We also denote by U(t), $t\geq 1$
, the $(1-1/t)$
-quantile of F:
 \begin{equation} U(t)\,:\!=\, \bigg(\frac{1}{1-F}\bigg)^{\leftarrow}(t) = F^\leftarrow\bigg(1-\frac{1}{t}\bigg)=\inf\bigg\{x\in [0,\infty)\colon F(x)\geq 1-\frac{1}{t}\bigg\}, \quad t\geq 1.\end{equation}
In what follows the range of a distribution function is denoted by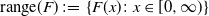 ${\rm range}(F)\,:\!=\,\{F(x)\colon x\in [0, \infty)\}$
. A realizable t-quantile of F is any value $z\in [0,\infty)$
such that $F(z)=t$
.
1.5. Organization
The rest of this paper is structured as follows. In Section 2 we provide results concerning the performance of single-threshold rules in the i.i.d. setting and related prophet inequalities. Section 3 discusses various statements about sharpness of prophet inequalities for single-threshold rules that have been made in antecedent literature. The main results of this paper are presented in Sections 4–6. Section 4 develops a game-theoretic formulation that characterizes sharp prophet inequalities and corresponding least favorable distributions and optimal single-threshold stopping rules. In Section 5 we detail how this game-theoretic characterization can be leveraged towards theoretical guarantees, and discuss the computational aspects related to the underlying optimization problems. Section 6 contains discussion and examples that illustrate application of the developed approach for restricted families of probability distributions. Section 7 presents proofs of the main results of the paper.
2. Single-threshold stopping rules
We slightly extend the definition of the single-threshold stopping rules in (8) to allow randomization. Let $\{\xi_t, 1\leq t\leq n\}$
be i.i.d. Bernoulli random variables with success probability $p\in [0,1]$
, independent of ${\mathscr X}$
. Define
 \begin{equation} \tau_p(\theta)\,:\!=\, \min\big\{1\leq t\leq n-1\colon (X_t>\theta)\cup (X_t=\theta,\xi_t=1)\big\},\end{equation}
and $\tau_p(\theta)=n$
if the set is empty. In words, $\tau_p(\theta)$
stops at the first time t when the observed value $X_t$
exceeds the fixed threshold $\theta$
, or if $X_t=\theta$
and the outcome $\xi_t$
of the independent Bernoulli trial with success probability p equals 1. Let
 \begin{align*}{\mathscr T}_{\rm s, r}\,:\!=\,\{\tau_p(\theta)\colon \theta\geq 0,\,p\in [0,1]\}\end{align*}
be the set of all such stopping rules. The stopping rule $\tau_p(\theta)$
is determined by two parameters: the threshold $\theta$
and the success probability p. Note that ${\mathscr T}_0$
and ${\mathscr T}_1$
are subsets of ${\mathscr T}_{\rm s,r}$
corresponding to $p=0$
and $p=1$
respectively.
The randomization in the construction of $\tau_p(\theta)$
admits very simple interpretation in terms of the stopping rules $\tau_0(\theta)$
and $\tau_1(\theta)$
defined in (8). If, for a given threshold $\theta$
, both rules $\tau_0(\theta)$
and $\tau_1(\theta)$
prescribe stopping at the same time instance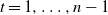 $t=1, \ldots, n-1$
then $\tau_p(\theta)=t$
as well. But if $\tau_1(\theta)=t$
and $\tau_0(\theta)>\tau_1(\theta)$
then the decision to stop or not to stop at t is made according to the outcome of the independent Bernoulli experiment with success probability p.
We begin with the result that establishes the exact formula for the reward of the optimal single-threshold stopping rule from ${\mathscr T}_{\rm s, r}$
.
Theorem 1. (Performance of optimal single-threshold rules.) Let $X_1, \ldots, X_n$
be i.i.d. random variables with common distribution F, and
 \begin{equation} \Delta(x) \,:\!=\, F(x)-F(x\!-\!), \qquad F_p(x) \,:\!=\, pF(x-) + (1-p)F(x) \quad {for\, all}\ x,\,p\in [0,1]. \end{equation}
Then
 \begin{align} V_n^*({\mathscr T}_{\rm s, r};\,F) & = \sup\nolimits_{\theta\geq 0,\,p\in[0,1]}\bigg\{\big[1-F_p^{n}(\theta)\big] \bigg[\theta + \frac{\int_{\theta}^\infty(1-F_p(x))\,\mathrm{d} x}{1-F_p(\theta)}\bigg] \nonumber \\ & \qquad\qquad\qquad\qquad + F_p^{n-1}(\theta)\bigg[\int_{[0,\theta]}x\,\mathrm{d} F(x) - p\theta\Delta(\theta)\bigg]\bigg\} \end{align}
 \begin{align} \kern3.5pc & = \sup\nolimits_{\theta\geq 0,\,p\in[0,1]}\bigg\{\big[1-F_p^{n-1}(\theta)\big] \bigg[\theta + \frac{\int_{\theta}^\infty(1-F_p(x))\,\mathrm{d} x}{1-F_p(\theta)}\bigg] \nonumber \\ & \qquad\qquad\qquad\qquad + F_p^{n-1}(\theta)\int_0^\infty[1-F_p(x)]\,\mathrm{d} x\bigg\}. \end{align}
Remark 1. Letting $p=0$
or $p=1$
in (13) and (14), we obtain the exact formulas for the reward of the optimal single-threshold stopping rules from ${\mathscr T}_{\rm s}$
.
Remark 2. Since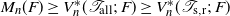 $M_n(F) \geq V_n^*({\mathscr T}_{\rm all};\,F)\geq V_n^*({\mathscr T}_{\rm s, r};\,F)$
, the theorem implies lower bounds on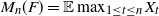 $M_n(F)=\mathbb E \max_{1\leq t\leq n} X_t$
, and on the performance of the optimal stopping rule in the class of all stopping rules, $V_n^*({\mathscr T}_{\rm all};\,F)$
. It is worth noting that (13) provides an improvement of Markov’s inequality for random variables of the type $\max_{1\leq t\leq n}X_t$
, where $X_1, \ldots, X_n$
are non-negative i.i.d. random variables. To see this, observe that for $p=0$
we have $F_0=F$
,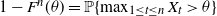 $1-F^n(\theta)={\mathbb P}\{\max_{1\leq t\leq n} X_t>\theta\}$
for all $\theta$
, and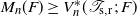 $M_n(F)\geq V_n^*({\mathscr T}_{\rm s,r};\, F)$
.
Some implications of Theorem 1 are contained in the following two corollaries.
Corollary 1. Let $X_1, \ldots, X_n$
be i.i.d. random variables with common distribution $F\in \mathcal{F}_{[0,\infty)}$
. Then
 \begin{equation} V_n^*({\mathscr T}_{\rm s, r};\, F) \geq \bigg[1-\bigg(1-\frac{1}{n}\bigg)^{n-1}\bigg]M_n(F) + \bigg(1-\frac{1}{n}\bigg)^{n-1}M_1(F). \end{equation}
Moreover, for every n,
 \begin{equation} \mathcal{R}_n({\mathscr T}_{\rm s, r};\,F) \geq 1 - \bigg(1-\frac{1}{n}\bigg)^n \geq 1 - \frac{1}{{\mathrm{e}}} \quad {for\, all}\ F\in \mathcal{F}_{[0,\infty)}. \end{equation}
Proof. Let $\theta=U(n)$
, and
 \begin{equation} p= \begin{cases} 0, & F(U(n))= 1-1/n, \\ \dfrac{F(U(n))-(1-{1}/{n})}{F(U(n))- F(U(n)\!-\!)}, & {\rm otherwise}, \end{cases} \end{equation}
where U(t) is the $(1-1/t)$
-quantile of distribution F [see (10)]. With this choice of p,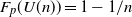 $F_p(U(n))=1-1/n$
, and therefore it follows from (14) that
 \begin{align*} V_n^*({\mathscr T}_{\rm s, r};\, F) \geq V_n(\tau_p(U(n));\, F) & = \big[1-F_p^{n-1}(U(n))\big]\bigg\{U(n) + n\int_{U(n)}^\infty[1-F(x)]\,\mathrm{d} x\bigg\} \\ & \quad + F_p^{n-1}(U(n))\int_0^\infty[1-F(x)]\,\mathrm{d} x. \end{align*}
Note also that
 \begin{equation} M_n(F)=\int_0^\infty [1-F^n(x)]\,\mathrm{d} x \leq U(n)+n\int_{U(n)}^\infty[1-F(x)]\,\mathrm{d} x. \end{equation}
Therefore,
 \begin{equation*} V_n^*({\mathscr T}_{\rm s, r};\, F) \geq V_n(\tau_p(U(n));\, F) = \bigg[1-\bigg(1-\frac{1}{n}\bigg)^{n-1}\bigg]M_n(F) + \bigg(1-\frac{1}{n}\bigg)^{n-1}M_1(F), \end{equation*}
as claimed in (15). The same chain of inequalities applied to (13) leads to
 \begin{equation} V_n^*({\mathscr T}_{\rm s, r};\, F) \geq \bigg[1-\bigg(1-\frac{1}{n}\bigg)^{n}\bigg]M_n(F) + \bigg(1-\frac{1}{n}\bigg)^{n-1}\int_{[0,U(n))} x\,\mathrm{d} F(x), \end{equation}
which implies (16).
The proof shows that inequality (16) holds for the stopping rule $\tau_p(\theta)$
with threshold $\theta=U(n)$
and parameter p defined in (17). Note that if the class ${\mathscr T}_{\rm s}$
is considered, then (16) is still fulfilled, but only for all distributions F with realizable $(1-1/n)$
-quantile. Thus, the following non-asymptotic prophet inequality holds:
 \begin{align*}\mathcal{R}^*_n({\mathscr T}_{\rm s};\, \mathcal{G}^n) \geq 1- (1-{1}/{n})^n \geq 1-{1}/{{\mathrm{e}}}\end{align*}
for all n, where
 \begin{align*}\mathcal{G}^n\,:\!=\,\{F\in \mathcal{F}_{[0,\infty)}\colon 1-{1}/{n}\in\ {\rm range}(F)\}.\end{align*}
Note that the class $\mathcal{G}^n$
is rather rich: it includes all continuous distributions on $[0, \infty)$
, and discrete distributions with realizable $(1-1/n)$
-quantile. In particular, if $F\in \mathcal{C}_{[0,\infty)}$
then, obviously,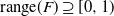 ${\rm range}(F)\supseteq [0,1)$
and $\mathcal{C}_{[0,\infty)} \subset \mathcal{G}^n$
for all n. Therefore,
 \begin{align*}\mathcal{R}_n^*\big({\mathscr T}_{\rm s};\, \mathcal{C}_{[0,\infty)}\big) \geq1 - (1-{1}/{n})^n \geq 1-{1}/{{\mathrm{e}}}\end{align*}
for all n. The above prophet inequality holds asymptotically as $n\to\infty$
under much weaker conditions when F is continuous on the right tail. In particular, if, for $x_0>0$
,
 \begin{align*} \mathcal{C}_{[0,\infty)}(x_0)\,:\!=\,\big\{ F\in \mathcal{F}_{[0,\infty)}\colon F \hbox{ is continuous on } [x_0, \infty)\big\}, \end{align*}
then for any $x_0>0$
there exists $n_0=n_0(x_0)$
such that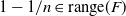 $1-1/n \in {\rm range}(F)$
for all $n\geq n_0$
. Therefore,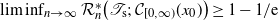 $\liminf_{n\to\infty}\mathcal{R}_n^*\big({\mathscr T}_{\rm s};\, \mathcal{C}_{[0,\infty)}(x_0)\big) \geq 1-{1}/{{\mathrm{e}}}$
.
Remark 3. The inequality (19) implies that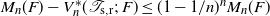 $M_n(F)-V_n^*({\mathscr T}_{\rm s, r};\, F) \leq (1-{1}/{n})^n M_n(F)$
, and therefore
 \begin{equation} \mathcal{A}_n^*\big({\mathscr T}_{\rm s, r};\, \mathcal{F}_{[0,1]}\big) \leq \bigg(1- \frac{1}{n}\bigg)^n. \end{equation}
A similar difference-type prophet inequality with constant $(1-1/n)^n$
has been established in the literature for the problem of stopping the sequence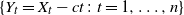 $\{Y_t=X_t- ct\colon t=1, \ldots, n\}$
with the cost of observation $c\geq 0$
, where $X_1, \ldots, X_n$
are independent [Reference Jones18] or i.i.d. [Reference Samuel-Cahn27] random variables. It is worth noting that the optimal rule in the stopping problem with the i.i.d. random variables and cost of observations is the single-threshold stopping rule, so there is a close connection between (20) and the results in [Reference Samuel-Cahn27]. It is proved in [Reference Samuel-Cahn27] that the constant $(1- 1/n)^n$
is sharp. However, sharpness of the inequality is understood not only in the sense of the least favorable distribution F, but also in the sense of the least favorable observation cost c. In fact, our results below demonstrate that inequality (20) can be improved when there is no observation cost, $c=0$
.
A byproduct of the proof of Corollary 1 is the following distribution-free inequality on the sequence $\{M_n(F), n\geq 1\}$
of maximal order statistics corresponding to sample sizes $n=1,2,\ldots$
This result is interesting in its own right.
Corollary 2. (Distribution-free bounds on the growth of expected extremes.) Let $X_1, X_2, \ldots$
be i.i.d. random variables with common distribution function F, and let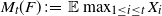 $M_t(F)\,:\!=\,\mathbb E\max_{1\leq i\leq t} X_i$
for any $t \geq 1$
. Then, for integers $n\geq 1$
and $k\geq 0$
and any $F \in \mathcal{F}_{[0,\infty)}$
,
 \begin{equation*} M_n(F) \geq (1-\lambda_{n,k})M_{n+k}(F) + \lambda_{n,k}M_1(F), \qquad \lambda_{n,k}\,:\!=\, \bigg(1-\frac{1}{n+k}\bigg)^{n-1}. \end{equation*}
Proof. It follows from (14) that, for any $\alpha\geq 1$
and $p\in [0,1]$
,
 \begin{align*} M_n(F) \geq V_n(\tau_p(U(\alpha));\, F) & = \big[1-F_p^{n-1}(U(\alpha))\big]\bigg\{U(\alpha) + \frac{\int_{U(\alpha)}^\infty[1-F(x)]\,\mathrm{d} x}{1-F_p(U(\alpha))}\bigg\} \\ & \quad + F_p^{n-1}(U(\alpha))\int_0^\infty[1-F(x)]\,\mathrm{d} x. \end{align*}
Choosing $\alpha=n+k$
and p such that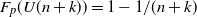 $F_p(U(n+k))= 1-1/(n+k)$
[see (17)] in the previous formula and applying (18) with n replaced by $n+k$
, we complete the proof.
Remark 4. [Reference Downey and Maier8] studies the rate of growth of the sequence $\{M_n(F), n\geq 1\}$
, and defines an ordering of distribution functions based on $\{M_n(F), n\geq 1\}$
. Among other results, this paper proves the inequality
 \begin{align*}M_n(F) \geq (1-{\mathrm{e}}^{-1})\big\{U(n) + n\int_{U(n)}^\infty[1-F(x)]\,\mathrm{d} x\big\}\quad \text{for all}\ F\in \mathcal{F}_{[0,\infty)}.\end{align*}
This is an immediate consequence of (13) with $\theta=U(n)$
and p given in (17). For additional results on the behavior of the sequence of expectations of the maximum of i.i.d. random variables we refer to [Reference Downey7].
3. Discussion
Some statements about sharpness of prophet inequalities for single-threshold stopping rules appeared in previous literature. Our discussion of these statements is divided into two parts. In the first part we discuss the results of [Reference Samuel-Cahn26], while the second part deals with results from the online auctions literature.
3.1. Results of [Reference Samuel-Cahn26]
It is shown in [Reference Samuel-Cahn26, Theorem 2] that for the class ${\mathscr T}_{\rm s}$
of single-threshold rules without randomization we have
 \begin{equation} \lim_{n\to\infty} \mathcal{R}^*_n({\mathscr T}_{\rm s};\, \mathcal{F}_{[0,\infty)}) = \frac{1}{2}.\end{equation}
In the proof of (21) [Reference Samuel-Cahn26] considers a discrete least favorable distribution $F_*$
having three atoms at 0, $a\in (0,1)$
, and 1 with respective probabilities $1-(b+c)/n$
, $c/n$
, and $b/n$
; here, $b>0$
, $c>0$
, and $b+c<n$
. Thus, the distribution $F_*$
is
 \begin{align*} F_*(x) = \begin{cases} 1 - \dfrac{b+c}{n}, & 0\leq x < a, \\ 1 - \dfrac{b}{n}, & a\leq x< 1, \\ 1, & x\geq 1. \end{cases} \end{align*}
In this example a straightforward calculation yields
 \begin{equation*} M_n(F_*) = a\bigg[\bigg(1-\frac{b}{n}\bigg)^n-\bigg(1-\frac{b+c}{n}\bigg)^n\bigg] + 1-\bigg(1-\frac{b}{n}\bigg)^n.\end{equation*}
For the stopping rule $\tau_0(\theta)$
in (8) there are three possible thresholds: $\theta=0$
, $\theta=a$
, and $\theta=1$
. In view of (14) with $p=0$
, the corresponding values are given by
 \begin{align*} \mathbb E X_{\tau_0(0)} & = \bigg[1-\bigg(1-\frac{b+c}{n}\bigg)^{n-1}\bigg]\frac{ac+b}{c+b} + \bigg(1-\frac{b+c}{n}\bigg)^{n-1}\frac{ac+b}{n}, \\ \mathbb E X_{\tau_0(a)} & = 1 - \bigg(1-\frac{b}{n}\bigg)^{n-1} + \bigg(1-\frac{b}{n}\bigg)^{n-1}\frac{ac+b}{n}, \\ \mathbb E X_{\tau_0(1)} & = \mathbb E(X_1) = \frac{ac+b}{n}.\end{align*}
Now, put $a= a_n= 1/n$
, $b=b_n= 1/n$
, and $c=c_n=\sqrt{n}$
, and let $F_n$
stand for the distribution $F_*$
with parameters $a_n$
, $b_n$
, and $c_n$
. Then, asymptotically, $M_n(F_n)\sim{2}/{n}$
, $\mathbb E X_{\tau_0(0)}\sim{1}/{n}$
, $\mathbb E X_{\tau_0(a_n)}\sim{1}/{n}$
, and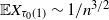 $\mathbb E X_{\tau_0(1)}\sim{1}/{n^{3/2}}$
, where $v_n\sim w_n$
means that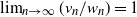 $\lim_{n\to\infty}(v_n/w_n)=1$
. Thus, the limit $\frac12$
is achieved asymptotically for $\mathcal{R}_n({\mathscr T}_{\rm s};\, F_n)$
.
It is instructive to calculate the competitive ratio of the best stopping rule from ${\mathscr T}_{\rm s,r}$
(the best rule with randomization) on the sequence of distributions $\{F_n\}$
defined above. Consider the stopping rule $\tau_p(\theta)$
defined in (11) with
 \begin{align*} \theta=a_n=\frac{1}{n}, \qquad p=p_n= \frac{F_n(a_n)-(1-{1}/{n})}{F_n(a_n)-F_n(a_n-)}=\frac{1-b_n}{c_n}=\frac{1-{1}/{n}}{\sqrt{n}}. \end{align*}
With this choice of parameters, in view of (13),
 \begin{align*} \mathbb E X_{\tau_{p_n}(a_n)} & = \bigg[1-\bigg(1-\frac{1}{n}\bigg)^n\bigg]\bigg[a_n+ n\int_{a_n}^\infty (1-F_n(x))\,\mathrm{d} x\bigg] \\ & \quad + \bigg(1-\frac{1}{n}\bigg)^{n-1}\bigg[\int_{[0,a_n]}x\,\mathrm{d} F_n(x) - p_na_n\Delta(a_n)\bigg] \\ & = \bigg[1-\bigg(1-\frac{1}{n}\bigg)^n\bigg]\big[a_n + b_n(1-a_n)\big] + \bigg(1-\frac{1}{n}\bigg)^{n-1}\bigg[\frac{a_n c_n}{n} - \frac{a_n(1-b_n)}{n}\bigg] \\ & = \bigg[1-\bigg(1-\frac{1}{n}\bigg)^n\bigg]\bigg(\frac{2}{n}- \frac{1}{n^2}\bigg) + \bigg(1-\frac{1}{n}\bigg)^{n-1}\frac{1}{n\sqrt{n}\,}\bigg[1-\frac{1}{\sqrt{n}\,}+\frac{1}{n\sqrt{n}\,}\bigg].\end{align*}
Since $M_n(F_n)\sim 2/n$
, on the sequence of distributions $\{F_n\}$
we obtain
 \begin{align*} \lim_{n\to\infty}\frac{\mathbb E X_{\tau_{p_n}(a_n)}}{M_n(F_n)} = 1-\frac{1}{{\mathrm{e}}}. \end{align*}
Thus, $\lim_{n\to\infty}\mathcal{R}_n^*({\mathscr T}_{\rm s, r};\, \mathcal{F}_{[0,\infty)}) = 1-{1}/{{\mathrm{e}}}$
, i.e. the prophet inequality (16) is asymptotically sharp for the single-threshold stopping rules with randomization, and it is achieved on the same sequence of worst-case distributions as the prophet inequality (21).
3.2. Online auctions literature
Recently there has been renewed interest in prophet inequalities due to relations between optimal stopping theory and the design of online auction mechanisms. In one such scenario, a seller has a single item to sell to n customers, where the ith customer, $i=1, \ldots, n$
, has a random valuation $X_i$
for the item. The valuations of different customers are assumed to be independent. The customers arrive sequentially, and they are presented with a price (perhaps, customer-dependent). The customer purchases the item if his/her valuation exceeds the quoted price. The goal of the seller is to design a pricing policy to maximize the revenue. This setting is often referred to as a posted-price auction.
The prophet secretary model in [Reference Ehsani, Hajiaghayi, Kesselheim and Singla9, Reference Esfandiari, Hajiaghayi, Liaghat and Monemizade10] assumes that the valuations $X_1, \ldots, X_n$
are independent random variables with distributions $F_1, \ldots, F_n$
, and customers arrive sequentially in a random order. This implies that the realized sequence of valuations is $X_{\pi_1}, \ldots, X_{\pi_n}$
, where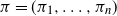 $\pi=(\pi_1, \ldots, \pi_n)$
is a random permutation of $\{1, \ldots, n\}$
, independent of $X_1, \ldots, X_n$
. Various pricing policies were studied in this setting and corresponding prophet inequalities were derived. We refer to [Reference Correa, Foncea, Hoeksma, Oosterwijk and Vredeveld5] for a review of results in this area.
It was shown in [Reference Correa, Foncea, Hoeksma, Oosterwijk and Vredeveld6] that, for continuous distribution functions,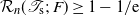 $\mathcal{R}_n({\mathscr T}_{\rm s};\, F) \geq 1-{1}/{{\mathrm{e}}}$
for all $F\in \mathcal{C}_{[0,\infty)}$
. A similar result was obtained in [Reference Ehsani, Hajiaghayi, Kesselheim and Singla9] for the class of all distributions $\mathcal{F}_{[0,\infty)}$
, but that paper considered stopping rules with random breaking of ties when the observed random variable $X_t$
is exactly equal to a chosen threshold. Theorem 21 in [Reference Ehsani, Hajiaghayi, Kesselheim and Singla9] claims that the prophet inequality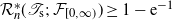 $\mathcal{R}_n^*({\mathscr T}_{\rm s};\, \mathcal{F}_{[0,\infty)})\geq 1-{\mathrm{e}}^{-1}$
is asymptotically sharp in the i.i.d. setting. In the proof of this statement the authors first consider the distribution $F_*$
having two atoms at $n/({\mathrm{e}}-1)$
and $({\mathrm{e}}-2)/({\mathrm{e}}-1)$
with respective probabilities $1/n^2$
and $1-1/n^2$
. For this distribution there are two possible choices of the threshold: $\theta_1=0$
and $\theta_2= ({\mathrm{e}}-2)/({\mathrm{e}}-1)$
. Then [Reference Ehsani, Hajiaghayi, Kesselheim and Singla9] showed that the best single-threshold stopping rule achieves the competitive ratio at most $0.58$
. Furthermore, the authors argued that this bound can be improved by randomization to $1-{\mathrm{e}}^{-1}$
.
For the distribution $F_*$
we have
 \begin{equation*} M_n(F_*) = \frac{{\mathrm{e}}-2}{{\mathrm{e}}-1}\bigg(1-\frac{1}{n^2}\bigg)^n + \frac{n}{{\mathrm{e}}-1}\bigg[1 - \bigg(1-\frac{1}{n^2}\bigg)^n\bigg].\end{equation*}
Using (14) for the single-threshold rule with no randomization ( $p=0$
), we obtain
 \begin{align*} \mathbb E X_{\tau_0(\theta_1)} & = \frac{{\mathrm{e}}-2}{{\mathrm{e}}-1}\bigg(1-\frac{1}{n^2}\bigg) + \frac{1}{n({\mathrm{e}}-1)}, \\ \mathbb E X_{\tau_0(\theta_2)} & = \frac{n}{{\mathrm{e}}-1}\bigg[1-\bigg(1-\frac{1}{n^2}\bigg)^{n-1}\bigg] + \bigg[\frac{{\mathrm{e}}-2}{{\mathrm{e}}-1}\bigg(1-\frac{1}{n^2}\bigg) + \frac{1}{n({\mathrm{e}}-1)}\bigg] \bigg(1-\frac{1}{n^2}\bigg)^{n-1}.\end{align*}
These formulas imply that
 \begin{align*} \lim_{n\to\infty} M_n(F_*)=1, \qquad \lim_{n\to\infty} \mathbb E X_{\tau_0(\theta_1)} = \frac{{\mathrm{e}}-2}{{\mathrm{e}}-1}, \qquad \lim_{n\to\infty} \mathbb E X_{\tau_0(\theta_2)} = 1, \end{align*}
so that for the specified distribution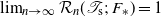 $\lim_{n\to\infty} \mathcal{R}_n({\mathscr T}_{\rm s};\, F_*)=1$
. Thus, for the distribution $F_*$
given in [Reference Ehsani, Hajiaghayi, Kesselheim and Singla9], the single-threshold stopping rules with no randomization (from ${\mathscr T}_{\rm s}$
) achieve a factor of one as $n\to\infty$
. In fact, for any distribution with two atoms the single-threshold rules achieve the factor one; this was pointed out in [Reference Samuel-Cahn26, Remark 1].
The difference between the above calculation and the conclusion in [Reference Ehsani, Hajiaghayi, Kesselheim and Singla9] stems from the fact that, in spite of the close connection between optimal stopping and online auctions, the algorithms considered in the latter area (see, e.g., [Reference Correa, Foncea, Hoeksma, Oosterwijk and Vredeveld6, Reference Ehsani, Hajiaghayi, Kesselheim and Singla9, Reference Esfandiari, Hajiaghayi, Liaghat and Monemizade10], etc.) are not completely equivalent to those in optimal stopping problems (see, e.g., [Reference Assaf, Goldstein and Samuel-Cahn1–Reference Chow, Robbins and Siegmund4, Reference Hill and Kertz15, Reference Hill and Kertz17, Reference Samuel-Cahn26], etc.). In particular, the decision rules in [Reference Correa, Foncea, Hoeksma, Oosterwijk and Vredeveld6, Reference Ehsani, Hajiaghayi, Kesselheim and Singla9, Reference Esfandiari, Hajiaghayi, Liaghat and Monemizade10] (which are fully in line with various other papers in this strand of literature) are left undefined on the event where the random variables $X_1, \ldots, X_n$
do not exceed the corresponding thresholds (see, e.g., Algorithm Prophet Secretary in [Reference Esfandiari, Hajiaghayi, Liaghat and Monemizade10, p. 1687] and [Reference Correa, Foncea, Hoeksma, Oosterwijk and Vredeveld6, Algorithm 1]). Strictly speaking, the considered decision rules are not stopping times because they do not take values in the stopping set $\{1, \ldots, n\}$
. Effectively, the implication of this fact is that if $X_1, \ldots, X_n$
are below the respective thresholds then the reward obtained is equal to zero. This formally corresponds to computation of the reward of a single-threshold rule without the last term on the right-hand side of (13). This distinction affects statements about sharpness of prophet inequalities derived in the online auctions literature, and the comparison across literatures should take this into consideration. In contrast, stopping times are naturally defined to be equal to the terminal value $X_n$
of the sequence at the end of the horizon n on the event when all observations are less than the corresponding thresholds, i.e. the last observation is selected. All this implies that sharpness of the inequality (16) for single-threshold stopping times does not follow from the results in [Reference Ehsani, Hajiaghayi, Kesselheim and Singla9].
In the next section we demonstrate that derivation of sharp non-asymptotic prophet inequalities for the stopping rules from the class ${\mathscr T}_{\rm s,r}$
is equivalent to the solution of an infinite two-person zero-sum game on the unit square with particular payoff kernels. The value of this game provides a sharp constant in the prophet inequality, while the optimal solution yields the corresponding least favorable distribution and optimal single-threshold stopping rule.
4. Game-theoretic characterization of prophet inequalities
Let us introduce the following notation. For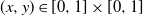 $(x, y)\in [0,1]\times [0,1]$
define
 \begin{align} R(x,y) &\,:\!= \frac{1-x^{n-1}}{1-y^n}\min\bigg\{1,\frac{1-y}{1-x}\bigg\} +x^{n-1}\frac{1-y}{1-y^n} = \begin{cases} \dfrac{1-x^{n-1}y}{1-y^n}, & x > y, \\[6pt] \dfrac{1-y}{1-y^n}\dfrac{1-x^n}{1-x}, & x < y, \\[4pt] 1, & x=y, \end{cases} \end{align}
 \begin{align} A(x,y) &\,:\!= 1 - y^n - (1-x^{n-1})\min\bigg\{1,\frac{1-y}{1-x}\bigg\} - x^{n-1}(1-y) \nonumber \\ & = \begin{cases} y(x^{n-1}-y^{n-1}), & x>y, \\[2pt] (1-y)\sum_{k=1}^{n-1}(y^k-x^k), & x\leq y. \end{cases}\\[6pt] \nonumber\end{align}
For probability distributions $\lambda$
and $\mu$
on [0,1] we put
 \begin{equation} \bar{R}(\lambda,\mu) \,:\!=\, \int_{0}^1\int_0^1 R(x,y)\,\mathrm{d}\lambda(x)\,\mathrm{d}\mu(y), \qquad \bar{A}(\lambda,\mu) \,:\!=\, \int_0^1\int_0^1 A(x,y)\,\mathrm{d}\lambda(x)\,\mathrm{d}\mu(y).\end{equation}
The main result of this section is given in the next theorem.
Theorem 2. (Saddlepoint characterization.) For any fixed n, the following representations hold:
 \begin{align} \mathcal{R}^*_n\big({\mathscr T}_{\rm s, r};\, \mathcal{F}_{[0,\infty)}\big) & = \textstyle\inf_\mu\sup_\lambda\big\{\bar{R}(\lambda,\mu)\colon \lambda\in\mathcal{F}_{[0,1]},\,\mu\in\mathcal{F}_{[0,1]}\big\}, \end{align}
 \begin{align} \mathcal{A}^*_n\big({\mathscr T}_{\rm s, r};\, \mathcal{F}_{[0,1]}\big) & = \sup\nolimits_\mu\textstyle\inf_\lambda\big\{\bar{A}(\lambda, \mu)\colon \lambda\in\mathcal{F}_{[0,1]},\,\mu\in\mathcal{F}_{[0,1]}\big\}, \\[6pt] \nonumber\end{align}
where $\mathcal{F}_{[0,\infty)}$
and $\mathcal{F}_{[0,1]}$
are the classes of all distributions on the respective domain.
Theorem 2 provides characterizations of the worst-case competitive ratio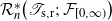 $\mathcal{R}^*_n\big({\mathscr T}_{\rm s,r};\, \mathcal{F}_{[0,\infty)}\big)$
and the worst-case regret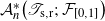 $\mathcal{A}^*_n\big({\mathscr T}_{\rm s, r};\, \mathcal{F}_{[0,1]}\big)$
via two-person zero-sum infinite games on the unit square. We refer to [Reference Karlin19] for detailed discussion of such problems. The interpretation of the games in (25) and (26) is evident: the decision-maker generates a random value x from distribution $\lambda$
on [0,1] and sets the stopping rule threshold $\theta_x= F^\leftarrow(x)$
and the success probability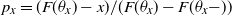 $p_x= (F(\theta_x)-x)/(F(\theta_x)-F(\theta_x\!-\!))$
, while nature selects the distribution $\mu$
on [0,1] which is directly related to the quantile function of F. In particular, as the proof of Theorem 2 shows, for the ratio-type prophet inequality the quantile function $F^{\leftarrow}$
of the least favorable distribution is related to the optimal solution of the game through the relationship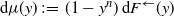 $\mathrm{d}\mu(y)\,:\!=\,(1-y^n)\,\mathrm{d} F^{\leftarrow}(y)$
for all $y \in [0,1]$
, while for the difference-type prophet inequality we have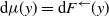 $\mathrm{d}\mu(y) = \mathrm{d} F^{\leftarrow}(y)$
, $y\in [0,1]$
.
Theorem 2 enables us to establish minimax results for the ratio-type and difference-type prophet inequalities.
Corollary 3. (Interchange results and minimax.) The infinite games (25) and (26) have solutions, that is,
 \begin{align} \textstyle\inf_{F\in \mathcal{F}_{[0,\infty)}}\sup\nolimits_{\tau \in {\mathscr T}_{\rm s,r}} \mathcal{R}_n(\tau;\, F) & = \sup\nolimits_{\tau\in{\mathscr T}_{\rm s,r}}\textstyle\inf_{F\in\mathcal{F}_{[0,\infty)}}\mathcal{R}_n(\tau;\, F), \end{align}
 \begin{align} \sup\nolimits_{F\in \mathcal{F}_{[0,1]}}\textstyle\inf_{\tau \in {\mathscr T}_{\rm s, r}}\mathcal{A}_n(\tau;\, F) & = \textstyle\inf_{\tau \in {\mathscr T}_{\rm s, r}}\sup\nolimits_{F\in \mathcal{F}_{[0,1]}} \mathcal{A}_n(\tau;\, F). \\[6pt] \nonumber\end{align}
The existence of the value of the infinite game (26) follows from the continuity of the payoff kernel A(x, y) on $[0,1]\times [0,1]$
; see, e.g., [Reference Kuhn23, Section 4.5]. Hence (28) holds. The kernel R(x, y) is positive, bounded above by one, but, in contrast to A(x, y), it is discontinuous at $(x,y)=(1,1)$
. Indeed, it follows from (22) that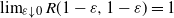 $\lim_{\varepsilon\downarrow 0} R(1-\varepsilon, 1-\varepsilon)=1$
, but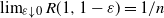 $\lim_{\varepsilon\downarrow 0} R(1, 1-\varepsilon)=1/n$
. However, R(x, y) is upper semi-continuous because for every sequence $\{(x_m, y_m)\}$
such that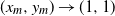 $(x_m, y_m)\to (1,1)$
as $m\to\infty$
we have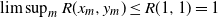 $\limsup_m R(x_m, y_m) \leq R(1,1)=1$
. Therefore (27) is a consequence of the minimax theorem in [Reference Glicksberg11].
It is worth mentioning that a game-theoretic interpretation of prophet inequalities has been discussed, e.g., in [Reference Meyerthole and Schmitz24, Reference Schmitz28]. For independent random variables [Reference Schmitz28] studies the question of the existence of minimax strategies in games against a prophet with ratio-type and difference-type payoff functions, while [Reference Meyerthole and Schmitz24] focuses on prophet games for martingales and general stochastic processes. Corollary 3 deals with i.i.d. random variables and single-threshold stopping rules; these results complement the ones in the aforementioned papers.
5. Computation of sharp constants
Theorem 2 shows that sharp constants in prophet inequalities for single-threshold stopping rules are determined by the optimal values of the two-person zero-sum infinite games on the unit square (25) and (26). These games can be approximated to any prescribed accuracy by finite games that are efficiently solved using simple computational procedures.
Specifically, for R(x, y) and A(x, y) defined in (22) and (23) and integer N, define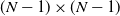 $(N-1)\times (N-1)$
matrices $R_N$
and $A_N$
as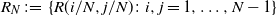 $R_N \,:\!=\, \{R({i}/{N},{j}/{N})\colon i,j= 1, \ldots, N-1\}$
and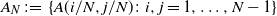 $A_N \,:\!=\, \{A({i}/{N},{j}/{N})\colon i,j= 1, \ldots, N-1\}$
, i.e.
 \begin{align} [R_N]_{ij} &\ :\!= \begin{cases} \dfrac{1-({i}/{N})^{n-1}({j}/{N})}{1-({j}/{N})^n}, & 1\leq j\leq i\leq N-1, \\[4mm] \dfrac{1-({i}/{N})^n}{1-{i}/{N}}\dfrac{1-{j}/{N}}{1-({j}/{N})^n}, & 1\leq i < j\leq N-1, \end{cases} \end{align}
 \begin{align} [A_N]_{ij} &\ :\!= \begin{cases} (1-{j}/{N})\sum_{k=1}^{n-1}[({j}/{N})^k - ({i}/{N})^k], & 1\leq i \leq j \leq N-1, \\[2mm] ({j}/{N})[({i}/{N})^{n-1} - ({j}/{N})^{n-1}], & 1\leq j < i\leq N-1. \end{cases} \\[6pt] \nonumber\end{align}
Consider the associated finite matrix games
 \begin{align} \mathcal{R}_{n, N}^* &\ :\!= \min_\mu\max_\lambda\big\{\lambda^{{\!\top}}R_N\mu\colon \lambda^{{\!\top}}\textbf{1} = 1,\,\mu^{{\!\top}}\textbf{1} = 1,\,\lambda\geq 0,\,\mu\geq 0\big\}, \end{align}
 \begin{align} \mathcal{A}_{n, N}^* &\ :\!= \max_\mu\min_\lambda\big\{\lambda^{{\!\top}}A_N\mu\colon \lambda^{{\!\top}}\textbf{1} = 1,\,\mu^{{\!\top}}\textbf{1} = 1,\,\lambda\geq 0,\,\mu\geq 0\big\}, \\[6pt] \nonumber\end{align}
where $\textbf{1}$
stands for the vector of ones, and $\lambda$
and $\mu$
correspond to the stopping strategy and the least favorable distribution respectively.
Our current goal is to establish bounds on the accuracy of approximation of optimal values of the inifnite games in (25) and (26), $\mathcal{R}_n^*\big({\mathscr T}_{\rm s, r};\, \mathcal{F}_{[0,\infty)}\big)$
and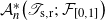 $\mathcal{A}_n^*\big({\mathscr T}_{\rm s, r};\, \mathcal{F}_{[0,1]}\big)$
, by the matrix games $\mathcal{R}_{n,N}^*$
and $\mathcal{A}_{n, N}^*$
respectively. First, we show that the optimal values $\mathcal{R}_{n,N}^*$
and $\mathcal{A}_{n, N}^*$
of matrix games (31) and (32) admit interpretations as the rewards of optimal single-threshold stopping rules for discrete distributions of special type.
Theorem 3. (Discrete approximations.) Consider the family of all discrete distribution functions with at most N atoms and probabilities taking values in the set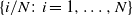 $\{i/N\colon i=1, \ldots, N\}$
:
 \begin{align*} \mathcal{D}_N \,:\!=\, \bigg\{F\colon F(x)=\frac{1}{N}\sum_{i=1}^NI\{u_i \leq x\},\, u=(u_1, \ldots, u_N)\in \mathcal{K}_+^N\bigg\}, \end{align*}
where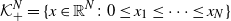 $\mathcal{K}_+^N=\{x\in {\mathbb R}^N\colon 0\leq x_1\leq \cdots \leq x_N\}$
. Then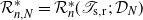 $\mathcal{R}_{n, N}^*=\mathcal{R}_n^*({\mathscr T}_{\rm s, r};\, \mathcal{D}_N)$
and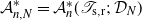 $\mathcal{A}_{n, N}^*=\mathcal{A}_n^*({\mathscr T}_{\rm s, r};\, \mathcal{D}_N)$
.
Theorem 3 shows that the optimal values of the finite matrix games in (31) and (32) provide sharp constants in the prophet inequalities for stopping rules in ${\mathscr T}_{\rm s,r}$
and the class of distributions $\mathcal{D}_N$
. It is worth mentioning that for fixed n and any $N_1$
and $N_2$
such that $N_1>N_2$
and $\mathcal{D}_{N_1}\subset \mathcal{D}_{N_2}$
, we have $\mathcal{R}_{n, N_1}^* \leq \mathcal{R}^*_{n, N_2}$
and $\mathcal{A}^*_{n, N_1}\geq \mathcal{A}^*_{n, N_2}$
. The proof of Theorem 3 also demonstrates that the least favorable distributions from $\mathcal{D}_N$
are fully determined by $N-1$
numbers $v_j$
,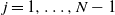 $j=1, \ldots, N-1$
, which are differences between the subsequent $(i/N)$
-quantiles of $F\in \mathcal{D}_N$
, $v_i\,:\!=\,u_{i+1}-u_i$
,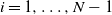 $i=1,\ldots, N-1$
.
The next statement provides bounds on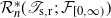 $\mathcal{R}_{n}^*({\mathscr T}_{\rm s, r};\, \mathcal{F}_{[0,\infty)})$
and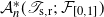 $\mathcal{A}_{n}^*({\mathscr T}_{\rm s, r};\, \mathcal{F}_{[0,1]})$
in terms of the optimal values of the matrix games (31) and (32).
Theorem 4. (Bounds for discrete approximations.)
-
(i) Let $\Delta_A\,:\!=\, ({n-1})/{2N}$
; then, for any
$n\geq 2$
, (33)
\begin{equation} \mathcal{A}_{n, N}^* \leq \mathcal{A}_n^*\big({\mathscr T}_{\rm s, r};\, \mathcal{F}_{[0,1]}\big) \leq \mathcal{A}_{n,N}^* + \Delta_A. \end{equation}
-
(ii) Let
then, for any
\begin{align*}\Delta_R\,:\!=\, \frac{n-1}{2N} \bigg[(1-{\mathrm{e}}^{-1})^2-\frac{1}{n-1}\bigg]^{-1};\end{align*}
$n\geq 4$
, (34)
\begin{equation} \mathcal{R}_{n, N}^* - \Delta_R \leq \mathcal{R}^*_n\big({\mathscr T}_{\rm s,r};\, \mathcal{F}_{[0,\infty)} \big) \leq \mathcal{R}_{n, N}^*. \end{equation}
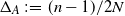


The theorem shows that sharp non-asymptotic constants in prophet inequalities for single-threshold rules in ${\mathscr T}_{\rm s,r}$
can be computed with any prescribed accuracy by solution of the finite games in (31) and (32). For any horizon n, choosing sufficiently large N, we can achieve the desired precision in computation of the sharp constants. In particular, the bounds of Theorem 4 show that in order to achieve a fixed precision $\varepsilon$
, the discretization parameter N should grow as n increases.
Note also that the left inequality in (33) and the right inequality in (34) follow straightforwardly from Theorem 3. According to this theorem the developed discrete approximation corresponds to the single-threshold stopping rules in ${\mathscr T}_{\rm s, r}$
. It is useful to note that the finite matrix games (31) and (32) that yield the bounds on the optimal constants in (33) and (34) can be expressed as linear programs which are efficiently solved using standard computational tools. We provide the details below.
5.1. Ratio-type prophet inequalities
To compute the sharp constants in ratio-type prophet inequalities we solve the game (31) as follows. Let $r_i^{{\top}}$
denote the ith row of matrix $R_N$
defined in (29), i.e. $R_N=[r_{1}^{{\!\top}};\,r_{2}^{{\!\top}};\,\ldots;\,r_{N-1}^{{\!\top}}]$
. Then the problem (31) is equivalent to
 \begin{align*} \min_\mu \max_{i=1,\ldots,N-1} r_i^{{\top}}\mu \quad {\rm such\ that}\quad \mu^{{\!\top}}\textbf{1}=1,\quad \mu \geq 0,\end{align*}
which is directly cast as the linear optimization problem
 \begin{equation} \min_{\mu,t} t \quad {\rm such\ that}\quad r_i^{{\top}}\mu \leq t, \ i=1, \ldots, N-1, \quad \mu^{{\!\top}}\textbf{1} = 1, \quad \mu\geq 0.\end{equation}
If $(\mu^*, t^*)$
is the optimal solution of (R) then the value of the matrix game (31) is $\mathcal{R}_{n, N}^*=t^*$
, and a least favorable distribution has at most N atoms with $(i/N)$
-quantiles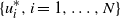 $\{u^*_i, i=1, \ldots, N\}$
which are determined by the relationship
 \begin{align*}u_1^*=0, \qquad u_{i+1}^*=\sum_{j=1}^i\frac{\mu_j^*}{1-({j}/{N})^n}, \quad i=1,\ldots, N-1.\end{align*}
Then the optimal stopping rule is associated with the threshold $\theta^*=u_{i^*+1}$
, where $i^*$
satisfies $r_{i_*}^{{\!\top}} \mu^*=t^*$
.
We solve problem (R) for different values of horizon $n\in\{10$
, 25, 50, 100, 300, 500, 1000, 2000, $3000\}$
with fixed discretization parameter $N=13\,500$
using the Mosek optimization solver [25]. This choice of N is dictated by computer power limitations (the computations were performed on a laptop with 32 GB RAM and an 11th-generation i7 processor). The results are reported in the second and third columns of Table 1. The second column presents the values $\mathcal{R}_{n, N}^*$
, while the third column gives the lower bound $\underline{\mathcal{R}}_{n, N}^*$
, which is the maximum of the lower bound of Theorem 4 and $1- (1-{1}/{n})^n$
, given by the prophet inequality (16):
 \begin{equation*} \underline{\mathcal{R}}_{n, N}^* = \max\big\{1-(1-{1}/{n})^n,\,\mathcal{R}_{n, N}^* - \Delta_R\big\}.\end{equation*}
Optimal values $\mathcal{R}^*_{n, N}$
and $\mathcal{A}_{n, N}^*$
of problems (R) and (A), and bounds on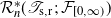 $\mathcal{R}^*_n({\mathscr T}_{\rm s, r};\,\mathcal{F}_{[0,\infty)})$
and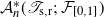 $\mathcal{A}_{n}^*({\mathscr T}_{\rm s,r};\, \mathcal{F}_{[0,1]})$
for different values of n, where $N=13\,500$
for problem (R) and $N=13\,000$
for problem (A).

Table 1 Long description
The table presents data for different values of n, specifically 10, 25, 50, 75, 100, 200, 500, 1000, 2000, and 3000. It includes columns for R sub n, N, R sub n, N asterisk, A sub n, N asterisk, and A sub n, N asterisk plus delta A. Each row lists the corresponding values for these columns. Row 1: n, 10; R sub n, N, 0.6698; R sub n, N asterisk, 0.669; A sub n, N asterisk, 0.1395; A sub n, N asterisk plus delta A, 0.140. Row 2: n, 25; R sub n, N, 0.6540; R sub n, N asterisk, 0.651; A sub n, N asterisk, 0.1572; A sub n, N asterisk plus delta A, 0.158. Row 3: n, 50; R sub n, N, 0.6458; R sub n, N asterisk, 0.641; A sub n, N asterisk, 0.1644; A sub n, N asterisk plus delta A, 0.166. Row 4: n, 75; R sub n, N, 0.6427; R sub n, N asterisk, 0.636; A sub n, N asterisk, 0.1671; A sub n, N asterisk plus delta A, 0.170. Row 5: n, 100; R sub n, N, 0.6411; R sub n, N asterisk, 0.634; A sub n, N asterisk, 0.1699; A sub n, N asterisk plus delta A, 0.172. Row 6: n, 200; R sub n, N, 0.6392; R sub n, N asterisk, 0.633; A sub n, N asterisk, 0.1708; A sub n, N asterisk plus delta A, 0.178. Row 7: n, 500; R sub n, N, 0.6409; R sub n, N asterisk, 0.632; A sub n, N asterisk, 0.1723; A sub n, N asterisk plus delta A, 0.191. Row 8: n, 1000; R sub n, N, 0.6468; R sub n, N asterisk, 0.632; A sub n, N asterisk, 0.1729; A sub n, N asterisk plus delta A, 0.211. Row 9: n, 2000; R sub n, N, 0.6595; R sub n, N asterisk, 0.632; A sub n, N asterisk, 0.1733; A sub n, N asterisk plus delta A, 0.250. Row 10: n, 3000; R sub n, N, 0.6726; R sub n, N asterisk, 0.632; A sub n, N asterisk, 0.1731; A sub n, N asterisk plus delta A, 0.288.
The accuracy of the presented bounds deteriorates as n grows; computation of more accurate bounds requires selecting much bigger values of N. For instance, in order to compute the sharp constant in the prophet inequality for $n=100$
with accuracy $10^{-3}$
, we need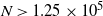 $N > 1.25\times 10^5$
, which leads to a linear program with non-sparse matrices of several hundred thousand dimensions.
From the numbers presented in the second and third columns of Table 1, some very useful conclusions on sharp constants can be reliably drawn. For instance, if $n=25$
then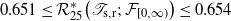 $0.651 \leq \mathcal{R}^*_{25}\big({\mathscr T}_{\rm s, r};\, \mathcal{F}_{[0,\infty)}\big) \leq 0.654$
.
5.2. Difference-type prophet inequalities
The sharp constants for the difference-type prophet inequality are obtained as solutions of the finite matrix game (32) with payoff matrix $A_N$
defined in (30). If $a_i^{{\top}}$
denotes the ith row of matrix $A_N$
, i.e.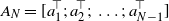 $A_N=[a_{1}^{{\!\top}};\, a_{2}^{{\!\top}};\,\ldots;\,a_{N-1}^{{\!\top}}]$
, then (32) is equivalent to the linear program
 \begin{equation} \max_{\mu,t} t \quad {\rm such\ that} \quad a_i^{{\top}}\,\mu \geq t,\ i=1, \ldots, N-1, \quad \mu^{{\!\top}}\textbf{1}= 1, \quad \mu\geq 0.\end{equation}
If $(\mu^*, t^*)$
is the optimal solution of (A) then $\mathcal{A}_{n, N}^*=t^*$
, and the least favorable distribution $F_*$
is the discrete distribution with $i/N$
-quantiles $u^*_i$
determined by $u_1^*=0$
, $u^*_{i+1} = \sum_{j=1}^i \mu_j^*$
,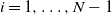 $i=1,\ldots, N-1$
.
Problem (A) is solved for $n\in\{10$
, 25, 50, 100, 300, 500, 1000, 2000, $3000\}$
and $N=13\,000$
. The last two columns in Table 1 contain the optimal value $\mathcal{A}_{n, N}^*$
and $\mathcal{A}_{n, N}^*+ \Delta_A$
, which are the lower and upper bounds on the sharp constant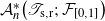 $\mathcal{A}_n^*\big({\mathscr T}_{\rm s, r};\, \mathcal{F}_{[0,1]}\big)$
in the difference-type prophet inequality. To the best of our knowledge, the existing literature does not contain prophet inequalities for single-threshold stopping rules in the i.i.d. setting. However, the numbers in the last two columns of Table 1 can be compared to the bounds on the values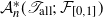 $\mathcal{A}_n^*({\mathscr T}_{\rm all};\, \mathcal{F}_{[0,1]})$
reported in [Reference Hill and Kertz16] for the class of all possible stopping rules: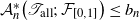 $\mathcal{A}_n^*\big({\mathscr T}_{\rm all};\, \mathcal{F}_{[0,1]}\big) \leq b_n$
with $b_{10\,000}\approx 0.111$
. The inferiority of the optimal single-threshold stopping rule in comparison with the optimal stopping rule is rather moderate; for example, for $n=200$
the regret increases from $0.11$
to $0.17$
.
6. Prophet inequalities for restricted families of distributions
The proofs of Theorems 2 and 3 heavily exploit the fact that both the expected value of the maximum,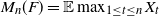 $M_n(F)=\mathbb E\max_{1\leq t\leq n} X_t$
, and the reward $V_n[\tau_{p_x}(\theta_x);\, F]$
of a single-threshold stopping rule with associated parameters $\theta_x$
and $p_x$
are linear functionals of the quantile function $F^\leftarrow$
. In particular, we show that
 \begin{align*} V_n(\tau_{p_x}(\theta_x);\, F) = \int_{0}^1\bigg[(1-x^{n-1})\min\bigg\{1,\frac{1-y}{1-x}\bigg\} + x^{n-1}(1-y)\bigg]\,\mathrm{d} F^\leftarrow(y),\end{align*}
and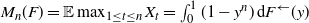 $M_n(F)= \mathbb E \max_{1\leq t\leq n} X_t = \int_{0}^{1} (1-y^n)\,\mathrm{d} F^\leftarrow(y)$
.
Another step in our derivation of the sharp constants is the approximation of F by the class of discrete distributions $\mathcal{D}_N$
. This allows us to reduce infinite-dimensional optimization problems to finite-dimensional ones and to efficiently solve them on a computer. It is worth noting that any distribution function F can be approximated in the ${\mathbb L}_\infty$
-norm by a function from $\mathcal{D}_N$
with accuracy $1/N$
. Since the value of N can be chosen (at least, theoretically) arbitrarily large, the sharp constants in prophet inequalities can be computed to any prescribed level of accuracy.
Specifically, the proof of Theorem 3 demonstrates that, for $F\in\mathcal{D}_N$
,
 \begin{align*} M_n(F) = d^{{\top}}v, \quad d = [d_1;\ldots;\,d_{N-1}], \quad d_j = 1-({j}/{N})^n,\ j= 1, \ldots, N-1\end{align*}
and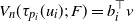 $V_n(\tau_{p_i}(u_i);\, F) = b_i^{{\top}}v$
, where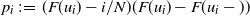 $p_i\,:\!=\, (F(u_i)-i/N)(F(u_i)-F(u_i-))$
, $b_i=[b_{i,1};\ldots;\,b_{i,N-1}]$
,
 \begin{align*} b_{i,j}= \begin{cases} 1-\bigg(\dfrac{i}{N}\bigg)^{n-1}\dfrac{j}{N}, & 1\leq j\leq i\leq N-1, \\[4mm] \dfrac{1-({i}/{N})^n}{1-{i}/{N}}\bigg(1-\dfrac{j}{N}\bigg), & 1\leq i < j\leq N-1, \end{cases}\end{align*}
and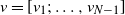 $v=[v_1;\ldots,v_{N-1}]$
, $u_1=0$
, $v_j=u_{j+1}-u_{j}$
,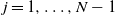 $j=1, \ldots, N-1$
with the $u_j$
being the $(j/N)$
-quantiles of F. Then the derivation of the ratio-type and difference-type prophet inequalities are formulated as the optimization problems
 \begin{align} \min_v\max_{i=1,\ldots,N-1}\frac{b_i^{{\top}}v}{d^{{\top}}v} \quad & {\rm such\ that} \quad v\geq 0, \end{align}
 \begin{align} \max_v\min_{i=1,\ldots,N-1}[d^{{\top}}v - b_i^{{\top}}v] \quad & {\rm such\ that} \quad \textbf{1}^{{\!\top}}v=1, \quad v\geq 0. \\[6pt] \nonumber\end{align}
It is readily seen that (35) and (36) are equivalent to (R) and (A) respectively. These problems are reduced to linear programs that are efficiently solved on a computer. The corresponding optimal values provide approximate sharp constants with the accuracy guarantees given in Theorem 4.
What is perhaps more important is that the proposed approach can be used to compute approximate sharp prophet inequalities for restricted families of distributions, such as distributions with bounded variance, second moment, or other constraints on the tail behavior. In fact, prophet inequalities under any condition on the quantile function that results in convex constraints in (35) and (36) can be efficiently computed. We illustrate this fact in the following two examples. In general, sharp constants in ratio-type and difference-type prophet inequalities for single-threshold rules can be efficiently computed for a variety of different families of distributions.
6.1. Difference-type prophet inequality for distributions with bounded variance
Let $\mathcal{F}_\sigma$
be the class of distribution functions on $[0,\infty)$
with variance bounded by a constant $\sigma^2<\infty$
,
 \begin{align*} \mathcal{F}_\sigma \,:\!=\, \bigg\{F\in\mathcal{F}_{[0,\infty)}\colon \operatorname{var}(X_i) = \int_{(0,1)}\int_{(0,1)}[x\wedge y-xy]\,\mathrm{d} F^{\leftarrow}(x)\,\mathrm{d} F^{\leftarrow}(y) \leq \sigma^2\bigg\}.\end{align*}
If $F\in \mathcal{F}_\sigma \cap \mathcal{D}_N$
then the condition $\operatorname{var}(X_i)\leq \sigma^2$
is equivalent to
 \begin{align*} \sum_{i=1}^{N-1}\sum_{j=1}^{N-1}\bigg(\frac{i}{N}\wedge\frac{j}{N} - \frac{ij}{N^2}\bigg) (u_{i+1}-u_{i})(u_{j+1}-u_{j}) = v^{{\top}}Qv,\end{align*}
where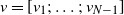 $v=[v_1;\ldots;\,v_{N-1}]$
with $v_i=u_{i+1}-u_{i}$
, and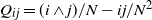 $Q_{ij}= ({i \wedge j})/{N} - {ij}/{N^2}$
,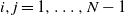 $i,j=1, \ldots, N-1$
.
Problem (35) associated with the ratio-type prophet inequality is scale invariant in the sense that its optimal solution is defined up to a scale parameter. Therefore the optimal value does not change when an upper bound on the variance is added. The same is true when any one-sided linear constraint on v is imposed. Therefore we discuss only the difference-type prophet inequality for the family $\mathcal{F}_\sigma\cap \mathcal{D}_N$
.
In this situation, in problem (36) the constraint $\textbf{1}^{{\!\top}}v=1$
should be replaced by the quadratic constraint $v^{{\top}}Qv\leq \sigma^2$
:
 \begin{equation*} \max_v\min_{i=1,\ldots,N-1}[d^{{\top}}v - b_i^{{\top}}v] \quad {\rm such\ that} \quad v^{{\top}}Qv \leq \sigma^2, \quad v\geq 0.\end{equation*}
The optimal value of this problem is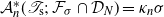 $\mathcal{A}_n^*({\mathscr T}_{\rm s};\, \mathcal{F}_\sigma\cap\mathcal{D}_N) = \kappa_n\sigma$
, where $\kappa_n$
is given by
 \begin{equation} \kappa_n \,:\!=\, \max_{z,t}\big\{t\colon(\textbf{1}d^{{\top}} - B)z - t\textbf{1} \geq 0,\, \|Q^{1/2}z\|_2 \leq 1,\,z\geq 0,\,t\geq 0\big\},\end{equation}
where $B=\{b_{i,j}\}$
,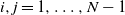 $i,j=1, \ldots, N-1$
. Table 2 displays values of $\kappa_n$
for $n\in\{10$
, 25, 50, 75, 100, 250, 500, 750, $1000\}$
obtained by solving the optimization problem in (37) for $N=7000$
; we used the CVX package for specifying and solving convex programs [Reference Grant and Boyd12] together with the Mosek optimization solver.
The values of $\kappa_n$
in (37) as a function of n.
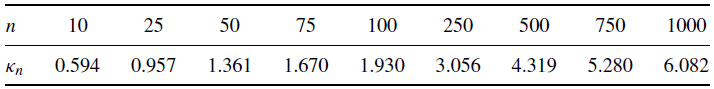
Table 2 Long description
A table with two columns and ten rows. The first column is labeled n and the second column is labeled kappa sub n. The values in the table are as follows: Row 1: n, 10; kappa sub n, 0.594. Row 2: n, 25; kappa sub n, 0.957. Row 3: n, 50; kappa sub n, 1.361. Row 4: n, 75; kappa sub n, 1.670. Row 5: n, 100; kappa sub n, 1.930. Row 6: n, 250; kappa sub n, 3.056. Row 7: n, 500; kappa sub n, 4.319. Row 8: n, 750; kappa sub n, 5.280. Row 9: n, 1000; kappa sub n, 6.082.
It can be seen that the sequence $\{\kappa_n\}$
increases with n. The growth of $\{\kappa_n\}$
can be compared with the results of [Reference Kennedy and Kertz20], which considered the setting of independent random variables, $F^{(n)}=\prod_{i=1}^nF_i$
, with the marginal distributions $F_i$
having bounded variance, ${\rm var}\{X_i\}\leq \sigma^2$
, $i=1, \ldots, n$
. They established an upper bound on the worst-case regret of the optimal stopping rules:
 \begin{align*} \mathcal{A}_n^*\big({\mathscr T}_{\rm all};\, \mathcal{F}_\sigma^{(n)}\big) = \sup\nolimits_{F^{(n)}\in\mathcal{F}_\sigma^{(n)}}\mathcal{A}_n\big({\mathscr T}_{\rm all};\, F^{(n)}\big) \leq c_n \sigma\sqrt{n-1},\end{align*}
where $c_n\leq \frac12$
,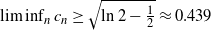 $\liminf_n c_n\geq \sqrt{\ln 2- \frac12}\approx 0.439$
. Since the setting of the i.i.d. random variables is a specific case, we also have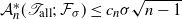 $\mathcal{A}^*_n({\mathscr T}_{\rm all};\, \mathcal{F}_\sigma)\leq c_n \sigma \sqrt{n-1}$
. Note that for large N, the value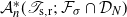 $\mathcal{A}^*_n({\mathscr T}_{\rm s, r};\, \mathcal{F}_\sigma\cap \mathcal{D}_N)$
approximates $\mathcal{A}^*_n({\mathscr T}_{\rm s, r};\, \mathcal{F}_\sigma)$
. For the data in Table 2 we have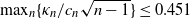 $\max_{n}\{\kappa_n/c_n\sqrt{n-1}\} \leq 0.451$
, where the maximum is taken over $n\in\{10$
, 25, 50, 75, 100, 250, 500, 750, $1000\}$
. Thus, the upper bound of [Reference Kennedy and Kertz20] is at least twice as high as the actual worst-case regret of the optimal single-threshold stopping rule on the class $\mathcal{F}_\sigma\cap \mathcal{D}_N$
with the values of n and N indicated above. Note, however, that [Reference Kennedy and Kertz20] considered a more general setting of independent random variables, and did not make statements on the sharpness of the derived prophet inequality.
6.2. Ratio-type prophet inequality for Pareto-like distributions
Let $1<p_1<p_0$
be real numbers and consider the family of distributions
 \begin{align*} \mathcal{F}(p_0,p_1) = \big\{F\in\mathcal{F}_{[1,\infty)}\colon 1-x^{-p_1} \leq F(x) \leq 1-x^{-p_0} \text{ for all } x\in [1,\infty)\big\}.\end{align*}
If $F\in \mathcal{F}(p_0,p_1)$
then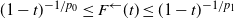 $(1-t)^{-1/p_0}\leq F^\leftarrow(t)\leq (1-t)^{-1/p_1}$
, and for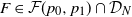 $F\in \mathcal{F} (p_0,p_1)\cap \mathcal{D}_N$
we have
 \begin{equation} q_{1,i}\,:\!=\,\bigg(\frac{N}{N-i}\bigg)^{1/p_0} \leq u_i \leq \bigg(\frac{N}{N-i}\bigg)^{1/p_1} \,=\!:\, q_{0,i}, \quad i=1,\ldots, N-1.\end{equation}
The condition in the definition of $\mathcal{F}(p_0,p_1)$
imposes restrictions on the distribution tail. Larger values of $p_1$
result in lighter distribution tails, and it is expected that in such a situation the worst-case competitive ratio of the single-threshold stopping rules will be closer to 1.
The optimal values $\mathcal{R}_n^*(p_0,p_1)$
of (39) as a function of n for $p_1=5$
, $p_0=20$
, and $N=7000$
.
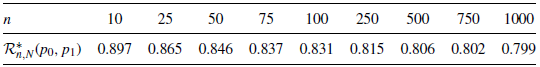
Table 3 Long description
A table with 12 rows and 12 columns. The first row contains the header ‘n’ followed by numerical values 10, 25, 50, 75, 100, 250, 500, 750, and 1000. The first column contains the header ‘R*_R,N(p0, p1)’ followed by numerical values 0.897, 0.865, 0.846, 0.837, 0.831, 0.815, 0.806, 0.802, and 0.799. The table presents the optimal values of R*_R,N(p0, p1) for different values of n and p. The values decrease as n increases.
The optimization problem associated with the family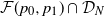 $\mathcal{F}(p_0,p_1)\cap \mathcal{D}_N$
takes the form
 \begin{equation} \min_v\max_{i=1,\ldots,N-1}\frac{b_i^{{\top}}v}{d^{{\top}}v} \quad {\rm such\ that} \quad q_1 \leq Qv \leq q_0, \quad v\geq 0,\end{equation}
where Q is the lower triangular matrix with all entries equal to one, and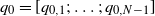 $q_0=[q_{0,1};\ldots;\, q_{0, N-1}]$
and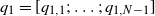 $q_1=[q_{1,1};\ldots;\, q_{1, N-1}]$
; see (38). The optimal values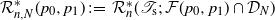 $\mathcal{R}^*_{n, N}(p_0,p_1)\,:\!=\,\mathcal{R}_n^*({\mathscr T}_{\rm s};\, \mathcal{F}(p_0,p_1)\cap \mathcal{D}_N)$
of (39) for $p_1=5$
, $p_0=20$
, $n\in \{10$
, 25, 50, 75, 100, 250, 500, 750, $1000\}$
computed with $N=7000$
are presented in Table 3. These values can be compared with values of $\mathcal{R}_{n, N}^*$
in Table 1. As expected,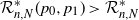 $\mathcal{R}^*_{n, N}(p_0,p_1)>\mathcal{R}_{n, N}^*$
because the family of distributions considered is narrower. Note also that the values of $\mathcal{R}^*_{n, N}(p_0,p_1)$
decrease as n increases.
7. Proofs of main results
7.1. Proof of Theorem 1
Proof. Let $\theta \geq 0$
be a fixed real number, $p\in [0,1]$
, and consider the stopping rule $\tau_p(\theta)$
defined in (11). In the subsequent proof, by convention we set $\prod_{j=1}^0 = 1$
.
We have
 \begin{align*} \mathbb E X_{\tau_p(\theta)} & = \mathbb E \sum_{t=1}^{n-1} X_t \big[1_{(X_t>\theta)} + 1_{(X_t=\theta, \xi_t=1)}\big] \prod_{j=1}^{t-1}\big[1_{(X_j<\theta)} + 1_{(X_j=\theta, \xi_j=0)}\big] \\ & \quad + \mathbb E X_n \prod_{j=1}^{n-1}\big[1_{(X_j<\theta)} + 1_{(X_j=\theta, \xi_j=0)}\big] \\ & = \big[\mathbb E X_t 1_{(X_t>\theta)} + \theta p \Delta(\theta)\big] \sum_{t=1}^{n-1}\big[F(\theta\!-\!)+ (1-p)\Delta(\theta)\big]^{t-1} \\ & \quad + \mathbb E X_n\big[F(\theta-)+ (1-p)\Delta(\theta) \big]^{n-1} \\ & = \big[\mathbb E X_t 1_{(X_t>\theta)} + \theta p \Delta(\theta)\big]\frac{1-F_p^{n-1}(\theta)}{1-F_p(\theta)} + F_p^{n-1}(\theta)\mathbb E X_n \\ & = \bigg[\theta(1-F_p(\theta)) + \int_\theta^\infty[1-F(x)]\,\mathrm{d} x\bigg]\frac{1-F_p^{n-1}(\theta)}{1-F_p(\theta)} + F_p^{n-1}(\theta) \mathbb E X_n, \end{align*}
and (14) follows because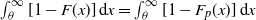 $\int_{\theta}^\infty[1-F(x)]\,\mathrm{d} x=\int_{\theta}^\infty[1-F_p(x)]\,\mathrm{d} x$
. Thus, (14) is proved.
Furthermore,
 \begin{align*} \mathbb E X_{\tau_p(\theta)} & = \mathbb E \sum_{t=1}^{n}X_t\big[1_{(X_t>\theta)} + 1_{(X_t=\theta, \xi_t=1)}\big] \prod_{j=1}^{t-1}\big[1_{(X_j<\theta)} + 1_{(X_j=\theta, \xi_j=0)}\big] \\ & \quad + \mathbb E X_n \prod_{j=1}^{n}\big[1_{(X_j<\theta)} + 1_{(X_j=\theta, \xi_j=0)}\big] \\ & = \big[\mathbb E X_t 1_{(X_t>\theta)} + \theta p \Delta(\theta)\big] \sum_{t=1}^n[F(\theta-) + (1-p)\Delta(\theta)]^{t-1} \\ & \quad + \big[\mathbb E X_n 1_{(X_n<\theta)} + \theta(1-p)\Delta(\theta)\big] [F(\theta-) + (1-p)\Delta(\theta)]^{n-1} \\ & = \bigg\{\theta(1-F_p(\theta)) + \int_\theta^\infty[1-F(x)]\,\mathrm{d} x\bigg\} \frac{1-F_p^{n}(\theta)}{1-F_p(\theta)} \\ & \quad + F_p^{n-1}(\theta)\bigg\{\int_{[0,\theta]}x\,\mathrm{d} F(x) - p\theta\Delta(\theta)\bigg\}. \end{align*}
This completes the proof of (13).
7.2. Proof of Theorem 2
Proof. Let $F\in \mathcal{F}_{[0,\infty)}$
be a fixed distribution, and for fixed $\theta\geq 0$
and $p\in [0,1]$
let $F_p(\theta)$
be defined in (12). For any $x\in [0,1]$
there exists a pair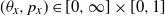 $(\theta_x, p_x)\in [0,\infty]\times [0,1]$
such that $F_{p_x}(\theta_x)=x$
. Indeed, by the definition of $F_p(\theta)$
,
-
(i) if
$\theta_x\,:\!=\, F^{\leftarrow}(x)$
and
$F(\theta_x)=x$
then, for any
$p_x\in [0,1]$
,
$F_{p_x}(\theta_x)=x$
; -
(ii) if
$\theta_x\,:\!=\,F^{\leftarrow}(x)$
and
$F(\theta_x)>x$
then, for
$p_x\,:\!=\, (F(\theta_x)-x)/(F(\theta_x)-F(\theta_x-))$
,
$F_{p_x}(\theta_x)=x$
.


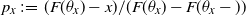

Then, according to (14), the reward of $\tau_{p_x}(\theta_x)$
is given by
 \begin{align} V_n(\tau_{p_x}(\theta_x);\, F) & = (1-x^{n-1})\bigg[F^\leftarrow(x)+\frac{1}{1-x}\int_{F^\leftarrow(x)}^\infty[1-F(t)]\,\mathrm{d} t\bigg] + x^{n-1}\int_0^\infty[1-F(x)]\,\mathrm{d} x \nonumber \\ & = (1-x^{n-1})\bigg[F^\leftarrow(x)+\frac{1}{1-x}\int_{x}^1(1-y)\,\mathrm{d} F^\leftarrow(y)\bigg] + x^{n-1}\int_{0}^1(1-y)\,\mathrm{d} F^\leftarrow(y) \nonumber \\ & = \int_{0}^1\bigg[(1-x^{n-1})\min\bigg\{1,\frac{1-y}{1-x}\bigg\} + x^{n-1}(1-y)\bigg]\,\mathrm{d} F^\leftarrow(y). \end{align}
Furthermore,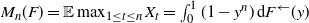 $M_n(F)= \mathbb E \max_{1\leq t\leq n} X_t = \int_{0}^{1} (1-y^n)\,\mathrm{d} F^\leftarrow(y)$
. Therefore the constant in the sharp ratio-type prophet inequality is equal to the optimal value of the optimization problem
 \begin{equation} \mathcal{R}^*_n({\mathscr T}_{\rm s,r};\, \mathcal{F}_{[0,\infty)}) = \inf_{F^\leftarrow}\sup\limits_{0\leq x\leq 1} \frac{\int_{0}^{1}\big[(1-x^{n-1})\min\{1,({1-y})/({1-x})\big\} + x^{n-1}(1-y)\big]\,\mathrm{d} F^\leftarrow(y)} {\int_{0}^{1}(1-y^n)\,\mathrm{d} F^\leftarrow(y)}, \end{equation}
where the infimum is taken over all quantile functions of probability distributions on $[0,\infty)$
. The problem is equivalent to
 \begin{equation} \begin{aligned} \textstyle\inf_{F^\leftarrow}\sup_{0\leq x\leq 1} \quad & \int_0^1\bigg[(1-x^{n-1})\min\bigg\{1,\frac{1-y}{1-x}\bigg\} + x^{n-1}(1-y)\bigg]\,\mathrm{d} F^\leftarrow(y) \\ {\rm such\ that} \quad & \int_0^1(1-y^n)\,\mathrm{d} F^\leftarrow(y)=1, \end{aligned} \end{equation}
Let $\mu$
be the right-continuous function such that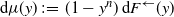 $\mathrm{d} \mu (y)\,:\!=\,(1-y^n)\,\mathrm{d} F^{\leftarrow}(y)$
for all $y\in [0,1]$
. Then $\mu$
is a probability distribution on [0,1]. Considering the randomized choice of $x\in [0,1]$
according to a distribution $\lambda$
on [0,1], we observe that the optimal values of (41) and (25) are equal. This proves the first statement of the theorem.
As for the game-theoretic representation for the difference-type prophet inequality, we observe that
 \begin{align*} \sup\limits_{F^\leftarrow}\inf_{0\leq x\leq 1}[M_n(F)-V_n(\tau_{p_x}(\theta_x);\, F)] = \sup\limits_{F^\leftarrow}\inf_{0\leq x\leq 1}\int_0^1 A(x, y)\,\mathrm{d} F^\leftarrow (y), \end{align*}
where the supremum is taken over all quantile functions of distributions on [0,1]. This constraint can be written in the form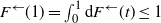 $F^{\leftarrow}(1)= \int_0^1 \mathrm{d} F^{\leftarrow}(t) \leq 1$
. Defining the right-continuous function $\mu$
such that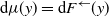 $\mathrm{d} \mu(y)= \mathrm{d} F^{\leftarrow}(y)$
and using the same reasoning as above, we come to (26).
7.3. Proof of Theorem 3
Proof. Assume that $F\in \mathcal{D}_N$
, i.e.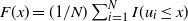 $F(x)=({1}/{N})\sum_{i=1}^N I(u_i\leq x)$
with some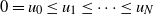 $0=u_0 \leq u_1\leq \cdots \leq u_N$
for $x\geq 0$
. For such distributions the set of all possible thresholds of stopping rules is restricted to the $(i/N)$
-quantiles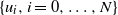 $\{u_i, i=0,\ldots,N\}$
of F. Define $v_0\,:\!=\, u_1$
, $v_j\,:\!=\,u_{j+1}-u_{j}$
, $j=1,\ldots,N-1$
. The quantile function $F^{\leftarrow}(u)$
of $F\in \mathcal{D}_N$
is given by $F^{\leftarrow}(u)=\sum_{j=0}^{N-1}v_jI\{{j}/{N} < u\leq({j+1})/{N}\}$
. Therefore, it follows from (40) that the reward of the stopping rule $\tau_{p_i}(u_i)$
with threshold $u_i$
,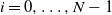 $i=0, \ldots, N-1$
, and randomization probability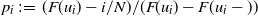 $p_i\,:\!=\, (F(u_i)-i/N)/(F(u_i)-F(u_i-))$
is
 \begin{align} V_n(\tau_{p_i}(u_i);\, F) & = \sum_{j=0}^{N-1}\bigg[\bigg(1-\bigg(\frac{i}{N}\bigg)^{n-1}\bigg) \min\bigg\{1,\frac{1-{j}/{N}}{1-{i}/{N}}\bigg\} + \bigg(\frac{i}{N}\bigg)^{n-1}\bigg(1-\frac{j}{N}\bigg)\bigg]v_j \nonumber \\ & = \sum_{j=0}^{N-1}R\bigg(\frac{i}{N},\frac{j}{N}\bigg)v_j, \end{align}
where $R(\cdot, \cdot)$
is given by (22). It follows from (43) that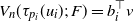 $V_n(\tau_{p_i}(u_i);\, F)= b_i^{{\top}}v$
,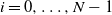 $i=0, \ldots, N-1$
, where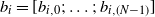 $b_i=[b_{i,0};\ldots;\,b_{i,(N-1)}]$
,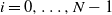 $i=0, \ldots, N-1$
, are vectors with entries
 \begin{align*} b_{i,j} = \begin{cases} 1-\bigg(\dfrac{i}{N}\bigg)^{n-1}\dfrac{j}{N}, & 0 \leq j\leq i\leq N-1, \\[4mm] \dfrac{1-({i}/{N})^n}{1-{i}/{N}}\bigg(1-\frac{j}{N}\bigg), & 0 \leq i < j\leq N-1. \end{cases} \end{align*}
Moreover, for $F\in\mathcal{D}_N$
we have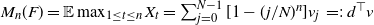 $M_n(F)=\mathbb E\max_{1\leq t\leq n}X_t=\sum_{j=0}^{N-1}[1-({j}/{N})^n]v_j \,=\!:\, d^{{\top}}v$
, where $d\in {\mathbb R}^{N}$
,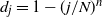 $d_j= 1-({j}/{N})^n$
,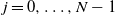 $j=0, \ldots, N-1$
. Then (42) implies that
 \begin{equation} \mathcal{R}^*_n({\mathscr T}_{\rm s,r};\, \mathcal{D}_N) = \max_\lambda\min_v\big\{\lambda^{{\!\top}}Bv\colon\lambda^{{\!\top}}\textbf{1}=1,\,d^{{\top}}v=1,\,\lambda\geq 0,\,v\geq 0\big\}, \end{equation}
where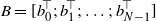 $B=[b_0^{{\!\top}};\,b_1^{{\!\top}};\ldots;\,b_{N-1}^{{\!\top}}]$
, and $\lambda$
stands for the probability vector that defines the single-threshold rule: the threshold $u_i$
is selected with the probability $\lambda_i$
,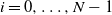 $i=0, \ldots, N-1$
. Observing that
 \begin{align*} \bigg[\frac{b_0^{{\!\top}}}{d_0}; \frac{b_1^{{\!\top}}}{d_1};\cdots;\frac{b_{N-1}^{{\!\top}}}{d_{N-1}}\bigg] = \bigg\{R\bigg(\frac{i}{N},\frac{j}{N}\bigg)\colon i,j=0,\ldots,N-1\bigg\} \,=\!:\, \tilde{R}_N, \end{align*}
we obtain that (44) is equivalent to
 \begin{equation} \mathcal{R}^*_n({\mathscr T}_{\rm s,r};\, \mathcal{D}_N) = \max_\lambda\min_\mu\big\{\lambda^{{\!\top}}\tilde{R}_N\mu\colon\lambda^{{\!\top}}\textbf{1}=1,\, \mu^{{\!\top}}\textbf{1}=1,\,\lambda\geq 0,\,\mu\geq 0\big\}. \end{equation}
To complete the proof that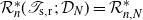 $\mathcal{R}^*_n({\mathscr T}_{\rm s,r};\, \mathcal{D}_N)=\mathcal{R}_{n, N}^*$
, we need to show that the optimal value of the above game with $N\times N$
matrix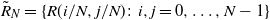 $\tilde{R}_N=\{R({i}/{N},{j}/{N})\colon i,j=0,\ldots,N-1\}$
coincides with the optimal value of the game with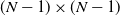 $(N-1)\times (N-1)$
matrix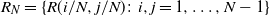 $R_N=\{R({i}/{N},{j}/{N})\colon i,j=1,\ldots,N-1\}$
. This fact is a consequence of the following dominance relationships between the rows and columns of matrix $\tilde{R}_N$
:
-
(i) The pure
$\lambda$
-strategy
$[1;\,0;\ldots;\,0]$
is dominated by the strategy
$[0;\,1;\,0\ldots;\,0]$
. Indeed, so that
\begin{align*} R(0,{j}/{N}) & = \frac{1-{j}/{N}}{1-({j}/{N})^n} \quad \text{for all}\ j=0,\ldots,N-1, \\ R({1}/{N},0) & = R({1}/{N},{1}/{N})=1, \\ R({1}/{N},{j}/{N}) & = \frac{1-({1}/{N})^n}{1-{1}/{N}}\frac{1-{j}/{N}}{1-({j}/{N})^n} \quad \text{for all}\ j=2,\ldots,N-1, \end{align*}
$R(0,0)=R({1}/{N},0)$
and
$R(0,{j}/{N})<R(1/N,{j}/{N})$
for all
$j=1,\ldots,N-1$
. Thus, the zeroth row of the matrix
$\tilde{R}_N$
may be eliminated.
-
(ii) The pure
$\mu$
-strategy
$[1;0;\ldots;\,0]$
is dominated by the strategy
$[0;1;0;\ldots;\,0]$
. Indeed, Thus,
\begin{align*} R({i}/{N}, 0) & = 1 \quad \text{for all}\ i=0, \ldots, N-1, \\ R(0,{1}/{N}) & = \frac{1-{1}/{N}}{1-({1}/{N})^n}, \\ R({i}/{N},{1}/{N}) & = \frac{1-({i}/{N})^{n-1}({1}/{N})}{1-({1}/{N})^{n}} \quad \text{for all}\ i=2,\ldots,N-1. \end{align*}
$R({i}/{N},0)>R({i}/{N},{1}/{N})$
for all
$i=0,\ldots, N-1$
, i.e. the zeroth column of matrix
$\tilde{R}_N$
can be eliminated.


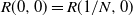
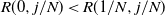


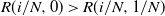
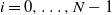

Facts (i) and (ii) together with (45) and the definition of $\mathcal{R}^*_{n, N}$
in (31) imply that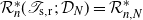 $\mathcal{R}^*_n ({\mathscr T}_{\rm s,r};\, \mathcal{D}_N)=\mathcal{R}_{n, N}^*$
.
To prove that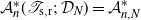 $\mathcal{A}_{n}^*({\mathscr T}_{\rm s,r};\, \mathcal{D}_N)= \mathcal{A}_{n, N}^*$
we note that with the introduced notation for any $F\in \mathcal{D}_N$
the regret of the stopping rule $\tau_{p_i}(u_i)$
associated with the threshold $u_i$
is
 \begin{align*} \mathcal{A}_n(\tau_{p_i}(u_i);\, F) = M_n(F)-V_n(\tau_{p_i}(u_i);\, F) = d^{{\top}}v - b_i^{{\top}}v, \quad i=0, \ldots, N-1. \end{align*}
For $F\in \mathcal{F}_{[0,1]}$
, $v^{{\top}}\textbf{1} \leq 1$
; therefore
 \begin{align*} \mathcal{A}_n^*({\mathscr T}_{\rm s,r};\, \mathcal{D}_N) & = \max_{v}\min_{i=1,\ldots,N-1}\{d^{{\top}}v - b_i^{{\top}}v\colon v^{{\top}}\textbf{1} \leq 1,\,v\geq 0\} \\ & = \max_{v}\min_{\mu}\big\{\mu^{{\!\top}}(\textbf{1}d^{{\top}}-B)v\colon \mu^{{\!\top}}\textbf{1}=1,\, v^{{\top}}\textbf{1} = 1,\,v\geq 0, \,\mu\geq 0\big\}. \end{align*}
Observe that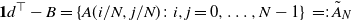 $\textbf{1}d^{{\top}}-B = \{A({i}/{N},{j}/{N})\colon i,j=0,\ldots,N-1\} \,=\!:\, \tilde{A}_N$
. Then the statement of the theorem follows from the fact that, similarly to above, the zeroth row and zeroth column of $\tilde{A}_N$
can be eliminated by dominance considerations.
7.4. Proof of Theorem 4
We begin with a simple lemma.
Lemma 1.
 \begin{align*} |A(x, y) - A(x^\prime, y)| & \leq (n-1)|x-x^\prime| \quad {for\, all}\ x,x^\prime,y \in [0,1], \\ |A(x, y) - A(x, y^\prime)| & \leq (n-1)|y-y^\prime| \quad {for\, all}\ x,y,y^\prime \in [0,1]. \end{align*}
Proof. We note that A(x, y) is continuous on $[0,1]^2$
. We have, for any $y\in [0,1]$
,
 \begin{align*} \bigg|\frac{\partial A(x,y)}{\partial x}\bigg| & = (n-1)yx^{n-2} \leq n-1 \quad \text{for all}\ (x,y) \ \colon x > y, \\ \bigg|\frac{\partial A(x,y)}{\partial x}\bigg| & = (1-y)\sum_{k=1}^{n-1}kx^{k-1} \\ & = (1-y)\frac{\sum_{j=0}^{n-2}(j+1)x^{\,j}}{\sum_{j=0}^{n-2}x^{\,j}}\sum_{j=0}^{n-2}x^{\,j} \\ & \leq \bigg(\frac{1-y}{1-x}\bigg)\max_{j=0,\ldots,n-2}\{(j+1)\} \leq n-1 \quad \text{for all}\ (x,y) \ \colon x < y. \end{align*}
Therefore, for any fixed $y\in [0,1]$
, if $x > y$
and $x^\prime > y$
then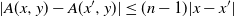 $|A(x, y) - A(x^\prime, y)|\leq (n-1)|x-x^\prime|$
, and the same inequality holds for any fixed $y\in [0,1]$
and $x < y$
, $x^\prime < y$
. Thus, for any $y\in [0,1]$
,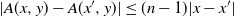 $|A(x, y) - A(x^\prime, y)|\leq (n-1)|x-x^\prime|$
for all $x, x^\prime\in [0,1]$
. Similarly, for any $x\in [0,1]$
,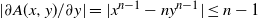 $|{\partial A(x,y)}/{\partial y}| = |x^{n-1}-n y^{n-1}|\leq n-1$
for all $(x,y)\colon x>y$
. For $x < y$
we have
 \begin{align*} \frac{\partial A(x,y)}{\partial y} & = \sum_{k=1}^{n-1}ky^{k-1} - \sum_{k=1}^{n-1}(k+1)y^k + \sum_{k=1}^{n-1}x^k \leq \sum_{k=1}^{n-1}ky^{k-1}(1-y) \\ & \leq \frac{\sum_{k=1}^{n-1}ky^{k-1}}{\sum_{k=1}^{n-1}y^{k-1}}(1-y)\sum_{k=1}^{n-1}y^{k-1} \leq \max_{j=0,\ldots,n-2}\{(j+2)\} \leq n-1. \end{align*}
On the other hand, the above expression implies that
 \begin{align*} \frac{\partial A(x,y)}{\partial y} = 1-ny^{n-1} + \sum_{k=1}^{n-1} x^k \geq 1-n. \end{align*}
Thus,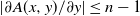 $|\partial A(x,y)/\partial y|\leq n-1$
, which implies that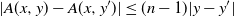 $|A(x, y) - A(x, y^\prime)|\leq (n-1) |y-y^\prime|$
for all $(x,y)\colon x<y$
. This completes the proof of the lemma.
Proof of Theorem 4(i). For brevity we write $\mathcal{A}^*_n=\mathcal{A}_n^*({\mathscr T}_{\rm s,r};\, \mathcal{F}_{[0,1]})$
, and recall that $\mathcal{A}_n^*=$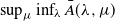 $\sup_\mu \inf_\lambda \bar{A}(\lambda, \mu)$
, where $\bar{A}(\lambda,\mu)$
is defined in (24). Consider the finite matrix game (32) associated with $A_N$
whose value is $\mathcal{A}^*_{n, N}$
. Assume that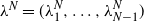 $\lambda^{N}=(\lambda_1^N,\ldots,\lambda^N_{N-1})$
and $\mu^N=(\mu_1^N,\ldots,\mu_{N-1}^N)$
are the optimal mixed strategies in this game, i.e.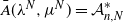 $\bar{A}(\lambda^N, \mu^N)=\mathcal{A}_{n, N}^*$
.
Let $\delta_y$
denote the degenerate distribution at $y\in [0,1]$
. First, we note that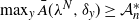 $\max_y \bar{A}(\lambda^N, \delta_y) \geq \mathcal{A}_n^*$
. Therefore, there exists a point y, say $y_*$
, such that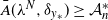 $\bar{A}(\lambda^N, \delta_{y_*}) \geq \mathcal{A}_n^*$
. By Lemma 1, there exists an index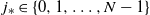 $j_*\in \{0, 1, \ldots, N-1\}$
such that
 \begin{equation*} \big|\bar{A}\big(\lambda^N, \delta_{y_*}\big) - \bar{A}\big(\lambda^N, \delta_{j_*/N}\big)\big| \leq \sum_{i=1}^{N-1}\lambda_i^N\bigg|A\bigg(\frac{i}{N},y_*\bigg)-A\bigg(\frac{i}{N},\frac{j_*}{N}\bigg)\bigg| \leq (n-1)\bigg|y_*-\frac{j_*}{N}\bigg| \leq \frac{n-1}{2N}. \end{equation*}
Therefore
 \begin{align*} \mathcal{A}_n^* \leq \bar{A}(\lambda^N,\delta_{y_*}) \leq \bar{A}(\lambda^N, \delta_{j_*/N}) + \frac{n-1}{2N} \leq \mathcal{A}^*_{n, N}+ \frac{n-1}{2N}, \end{align*}
which yields the upper bound in (33).
Furthermore, note that if $\delta_x$
is the degenerate distribution at $x\in [0,1]$
then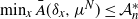 $\min_x \bar{A}(\delta_x, \mu^N)\leq \mathcal{A}_n^*$
. Therefore there exists $x_*$
such that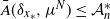 $\bar{A}(\delta_{x_*}, \mu^N)\leq \mathcal{A}_n^*$
. By Lemma 1, there exists an index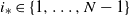 $i_*\in \{1, \ldots, N-1\}$
such that
 \begin{align*} \big|\bar{A}\big(\delta_{x_*}, \mu^N\big) - \bar{A}\big(\delta_{i_*/N}, \mu^N\big)\big| \leq \sum_{j=1}^{N-1}\mu_j^N\bigg|A\bigg(x_*,\frac{j}{N}\bigg) - A\bigg(\frac{i_*}{N},\frac{j}{N}\bigg)\bigg| \leq (n-1)\bigg|x_*-\frac{i_*}{N}\bigg| \leq \frac{n-1}{2N}. \end{align*}
Therefore
 \begin{align*} \mathcal{A}_n^* \geq \bar{A}(\delta_{x_*}, \mu^N) \geq \bar{A}(\delta_{i_*/N},\mu^N) - \frac{n-1}{2N} \geq \mathcal{A}_{n, N}^* - \frac{n-1}{2N}, \end{align*}
which completes the proof of statement (i).
We now require another auxiliary lemma.
Lemma 2. Let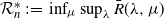 $\mathcal{R}_n^*\,:\!=\,\inf_\mu \sup_\lambda \bar{R}(\lambda, \mu)$
be the value of the game on the unit square with payoff kernel R(x,y) (see (22) and (24)), and let $\lambda_*$
and $\mu_*$
be the optimal strategies. Let
 \begin{equation} c_n\,:\!=\,-\ln \bigg\{1-(1-{\mathrm{e}}^{-1})^2+\frac{1}{n-1}\bigg\}. \end{equation}
If $n\geq 4$
then the interval $[1- c_n/n, 1]$
does not belong to the support of $\lambda_*$
.
Proof. Let $x_0=1- c/n$
for some $c \in (0,c_n)$
, and assume to the contrary that $x_0\in {\rm supp}(\lambda_*)$
. Under this assumption we have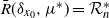 $\bar{R}(\delta_{x_0}, \mu^*)=\mathcal{R}_n^*$
; see, e.g., [Reference Karlin19, Lemma 2.2.1]. Now let $y_0=1-{1}/{n}$
; since $x_0>y_0$
, it follows from (22) that
 \begin{align*} \bar{R}(\delta_{x_0}, \delta_{y_0}) = R(x_0, y_0) & = \frac{1-(1-{c}/{n})^{n-1}(1-{1}/{n})}{1-(1-{1}/{n})^n} \\ & \leq \frac{1}{1-{\mathrm{e}}^{-1}}\bigg[1-\bigg(1-\frac{c}{n}\bigg)^n + \bigg(1-\frac{c}{n}\bigg)^n\frac{1-c}{n-c}\bigg]. \end{align*}
Because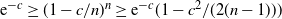 ${\mathrm{e}}^{-c} \geq (1-{c}/{n})^n \geq {\mathrm{e}}^{-c}(1-{c^2}/({2(n-1)}))$
we obtain
 \begin{align*} \bar{R}(\delta_{x_0}, \delta_{y_0}) & \leq \frac{1}{1-{\mathrm{e}}^{-1}}\bigg[1- {\mathrm{e}}^{-c}\bigg(1-\frac{c^2}{2(n-1)}-\frac{1}{n-c}\bigg)\bigg] \\ & \leq \frac{1}{1-{\mathrm{e}}^{-1}}\bigg[1-{\mathrm{e}}^{-c} + \frac{{\mathrm{e}}^{-c}(c^2+2)}{2(n-1)}\bigg]. \end{align*}
For $c\in (0,1)$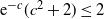 ${\mathrm{e}}^{-c}(c^2+2)\leq 2$
; therefore
 \begin{align*} \bar{R}(\delta_{x_0}, \delta_{y_0}) \leq \frac{1}{1-{\mathrm{e}}^{-1}}\bigg[1-{\mathrm{e}}^{-c}+\frac{1}{n-1}\bigg]. \end{align*}
This inequality shows that for any pair of numbers n and $c\in (0,1)$
such that
 \begin{equation} 1-{\mathrm{e}}^{-c}+ \frac{1}{n-1} < (1-{\mathrm{e}}^{-1})^2 \end{equation}
we obtain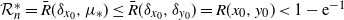 $\mathcal{R}^*_n = \bar{R}(\delta_{x_0},\mu_*) \leq \bar{R}(\delta_{x_0},\delta_{y_0}) = R(x_0,y_0) < 1-{\mathrm{e}}^{-1}$
. In particular, if $n\geq 4$
and
 \begin{align*} c_n= -\ln\bigg\{1-(1-{\mathrm{e}}^{-1})^2+\frac{1}{n-1}\bigg\} \approx -\ln\bigg\{0.6004 + \frac{1}{n-1}\bigg\} \end{align*}
then (47) holds for all $c\in (0,c_n)$
. This, however, stands in contradiction to inequality (16). Therefore $x_0\not\in {\rm supp}(\lambda_*)$
, and the proof is complete.
The next result is an analogue of Lemma 1 for the function R(x, y).
Lemma 3. For any $\varepsilon\in(0,1)$
,
 \begin{align} |R(x, y) - R(x^\prime, y)| & \leq \frac{n-1}{1-(1-\varepsilon)^n}|x-x^\prime| \ {for\, all}\ x,x^\prime \in [0,1-\varepsilon] \ {and\, all}\ y\in [0,1], \end{align}
 \begin{align} |R(x, y) - R(x, y^\prime)| & \leq \frac{n-1}{1-(1-\varepsilon)^n}|y-y^\prime| \ {for\, all}\ x\in [0,1-\varepsilon] \ {and\, all}\ y, y^\prime \in [0,1]. \\[6pt] \nonumber\end{align}
Proof. Let $y \in [0,1]$
be fixed. By (22), if $0\leq x < y\leq 1$
then
 \begin{equation*} \frac{\partial R(x,y)}{\partial x} = \frac{1-y}{1-y^n}\sum_{j=1}^{n-1}jx^{j-1} = \frac{\sum_{j=0}^{n-2}(j+1)x^{\,j}}{\sum_{j=0}^{n-2} x^{\,j}}\,\frac{\sum_{j=0}^{n-2}x^{\,j}}{\sum_{j=0}^{n-1}y^j} \leq \max_{0 \leq j\leq n-2}\{(j+1)\} \leq n-1, \end{equation*}
and for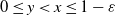 $0\leq y < x\leq 1-\varepsilon$
,
 \begin{equation*} \bigg|\frac{\partial R(x,y)}{\partial x}\bigg| = \frac{(n-1)x^{n-2} y}{1-y^n} \leq \frac{n-1}{1-(1-\varepsilon)^n}. \end{equation*}
In view of these inequalities, for all $x, x^\prime$
such that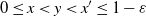 $0\leq x < y < x^{\prime}\leq 1-\varepsilon$
we have
 \begin{equation*} |R(x, y)- R(x^\prime, y)|\leq |R(x, y) - R(y,y)| + |R(y,y)- R(x^\prime, y)| \leq \frac{n-1}{1-(1-\varepsilon)^n} |x-x^\prime|. \end{equation*}
The inequalities imply (48).
Similarly, if $x\in [0,1-\varepsilon]$
is fixed and $x\leq y\leq 1$
, then
 \begin{align*} \bigg|\frac{\partial R(x,y)}{\partial y}\bigg| = \frac{1-x^n}{1-x}\frac{\sum_{j=0}^{n-2}(j+1)y^j}{\big(\sum_{j=0}^{n-1} y^j\big)^2} \leq \frac{\sum_{j=0}^{n-1} x^{\,j}}{\sum_{j=0}^{n-1} y^j}\frac{\sum_{j=0}^{n-2} (j+1)y^j}{\sum_{j=0}^{n-1} y^j} \leq \max_{0 \leq j\leq n-2} \{(j+1) \}\leq n-1, \end{align*}
and for $y < x\leq 1-\varepsilon$
,
 \begin{equation*} \frac{\partial R(x,y)}{\partial y} = -\frac{x^{n-1}}{1-y^n} + \frac{(1-x^{n-1}y)ny^{n-1}}{(1-y^n)^2}\leq \frac{(n-1)x^{n-1}}{1-y^n} \leq \frac{n-1}{1-(1-\varepsilon)^n}; \end{equation*}
the same inequality holds for $|\partial R(x,y)/\partial y|$
. Combining these inequalities we obtain (49).
Now, using Lemmas 2 and 3 we complete the proof of statement (ii) of Theorem 4.
Proof of Theorem 4(ii). The proof goes along the lines of the proof of statement (i), with the following minor changes: the payoff function A(x, y) is replaced by R(x, y), and the infinite game is considered on the rectangle $[0, 1- c_n/n]\times [0,1]$
. Lemma 2 ensures that the optimal values of the game on this set coincide with those on the unit square.
Recall that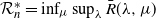 $\mathcal{R}_n^*=\inf_\mu \sup_\lambda \bar{R}(\lambda, \mu)$
, and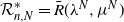 $\mathcal{R}_{n, N}^*= \bar{R}(\lambda^N, \mu^N)$
, where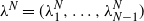 $\lambda^N=(\lambda_1^N, \ldots, \lambda_{N-1}^N)$
and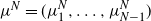 $\mu^N=(\mu_1^N, \ldots, \mu_{N-1}^N)$
are optimal mixing strategies in the finite matrix game (31). It follows from Lemma 2 that $\lambda^N_i=0$
for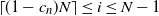 $\lceil (1-c_n)N\rceil\leq i\leq N-1$
, where $c_n$
is given in (46). The definitions imply that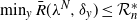 $\min_y \bar{R}(\lambda^N, \delta_y)\leq \mathcal{R}_n^*$
, i.e. there exists $y_*\in [0,1]$
such that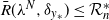 $\bar{R}(\lambda^N, \delta_{y_*})\leq \mathcal{R}_n^*$
. By Lemma 3 applied with $\varepsilon=c_n/n$
, for some $j_*$
,
 \begin{align*} \big|\bar{R}(\lambda^N, \delta_{y_*}) - \bar{R}(\lambda^N, \delta_{j_*/N})\big| \leq \frac{n-1}{1-(1-{c_n}/{n})^n}\bigg|y_*-\frac{j_*}{N}\bigg| \leq \frac{n-1}{2N\big(1-(1-{c_n}/{n})^n\big)}. \end{align*}
Therefore
 \begin{align*} \mathcal{R}_n^* \geq \bar{R}(\lambda^N, \delta_{y_*}) \geq \bar{R}(\lambda^N, \delta_{j_*/n}) - \frac{n-1}{2N(1-(1-{c_n}/{n})^n)} \geq \mathcal{R}_{n, N}^* - \frac{n-1}{2N(1-(1-{c_n}/{n})^n)}. \end{align*}
Then the lower bound in (34) follows by substitution of (46). The upper bound on $\mathcal{R}_n^*$
is proved similarly.
Acknowledgements
We would like to thank the Associate Editor and two anonymous referees for useful comments that led to improvements in the paper.
Funding information
The research is supported by BSF grant 2020063.
Competing interests
There were no competing interests to declare which arose during the preparation or publication process of this article.
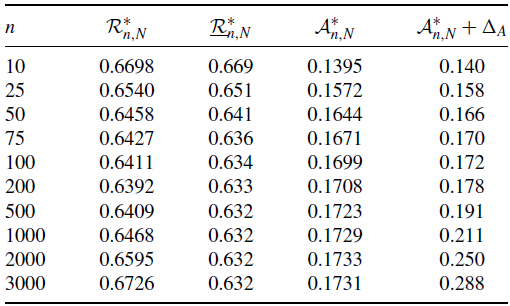
 Rn,N∗
 An,N∗
 Rn∗(Ts,r;F[0,∞))
 An∗(Ts,r;F[0,1])
 N=13500
 N=13000
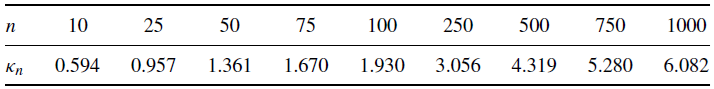
 κn
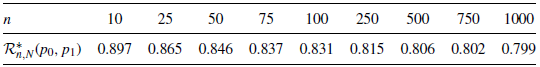
 Rn∗(p0,p1)
 p1=5
 p0=20
 N=7000

 Open access

