


No CrossRef data available.
Article contents
System IdentificationT. Söderström and P. Stoica Prentice Hall International, 1989
Review products
System Identification T. Söderström and P. Stoica Prentice Hall International, 1989
Published online by Cambridge University Press: 11 February 2009
Abstract
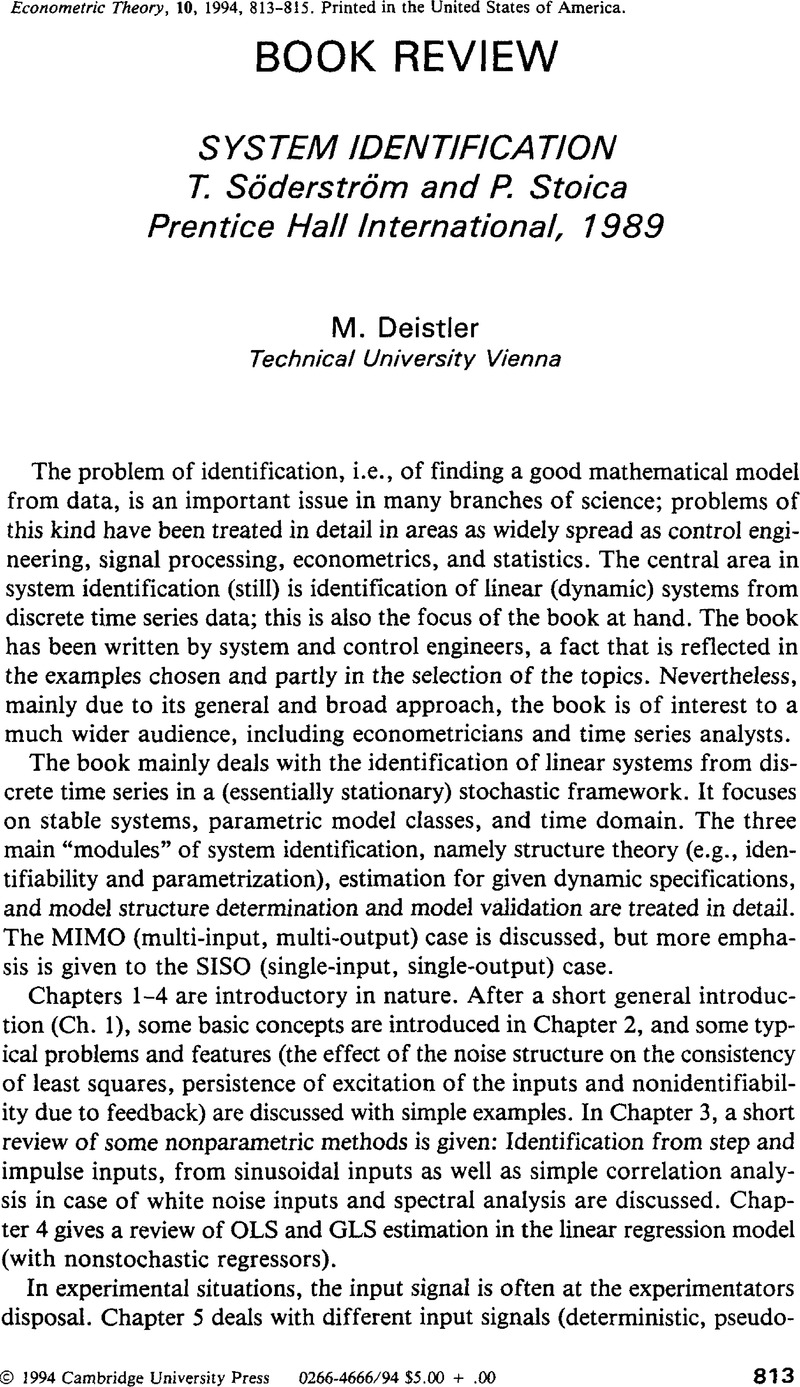
An abstract is not available for this content so a preview has been provided. Please use the Get access link above for information on how to access this content.
Information
- Type
- Book Review
- Information
- Copyright
- Copyright © Cambridge University Press 1994
References
REFERENCES
1.Åstrom, K.J. & Söderström, T.. Uniqueness of the maximum likelihood estimates of the parameters of an ARMA model. IEEE Transactions on Automatic Control AC-28 (1974): 773–786.Google Scholar
3.Dunsmuir, W. & Hannan, E.J.. Vector linear time series models. Advances in Applied Probability 8 (1976): 339–364.CrossRefGoogle Scholar
4.Hannan, E.J.The asymptotic theory of linear time series models. Journal of Applied Probability 10 (1973): 130–145.CrossRefGoogle Scholar
5.Hannan, E.J. & Deistler, M.. The Statistical Theory of Linear Systems. New York: Wiley, 1988.Google Scholar
6.Ljung, L.System Identification: Theory for the User. Englewood Cliffs: Prentice Hall, 1987.Google Scholar
7.Ljung, L. & Söderström, T.. Theory and Practice of Recursive Identification. Cambridge: MIT Press, 1983.Google Scholar
- 5
- Cited by